

Here we are again… and this time, we’re looking at what might be the single best business we’ve picked apart in the last three years.
Unlike some of our more speculative trades or a hopeful macro trending company; it’s a genuine small-cap compounder that’s yet to become giga popular in the twitosphere.
In our relentless hunt for the next asymmetric winner, companies like this are the exact reason we do the legwork. So… we’re already shareholders and we’re very freaking excited about this one, plus we’re also trying out an infographic heavy post which should make it more visual and interactive for you guys.
Even better: this deep dive is brought to you by our friends over at StockDashes.
Berkshire’s portfolio scores 84 on a K-shaped economy. What does yours score?
StockDashes rates your portfolio 0–100 against your own view of the economy, then shows which holdings fit that view and which don’t.
Import your broker export, choose your worldview, see your score in under a minute. Free account, no card.
Let’s break this fantastic company down.
As we now do every week for transparency, here is our list of past Pick of the Week posts and their returns since publishing:
All picks (equally weighted): +16.71%
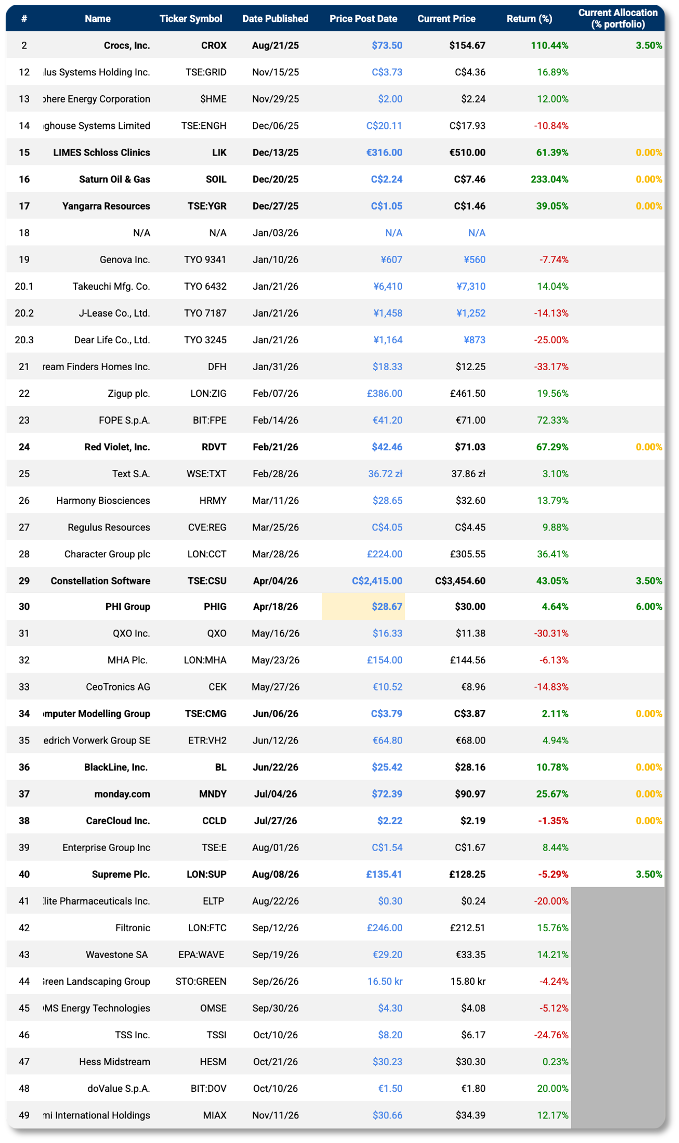
Note: We update one price, and that is #30 PHI Group (yellow highlight), to best represent our cost base given we increased our position in October. It is our largest individual name.

Pick of the Week. A curated series of high-conviction research on companies currently under our microscope. We screen for specific dislocations where the market has mispriced the balance sheet or earnings power (or both).
None of the following should be construed as investment advice. Please consult a financial advisor before making any investment decision. You will find a full disclaimer at the end of this post.


🏛️ Miami International Holdings Inc. ($MIAX)
⭐ Overall Grade: 10 / 10
Miami International Holdings, Inc. (NYSE: MIAX) is one of six companies building and managing digital arenas and ultra-fast private toll bridges for the stock market.
When big banks, algorithmic trading funds, and regular retail traders want to trade financial contracts, MIAX provides the venue and collects tolls. Historically, they’ve been mostly involved with options (especially commodities options), but today their market is growing in more than one way.
The Business Model
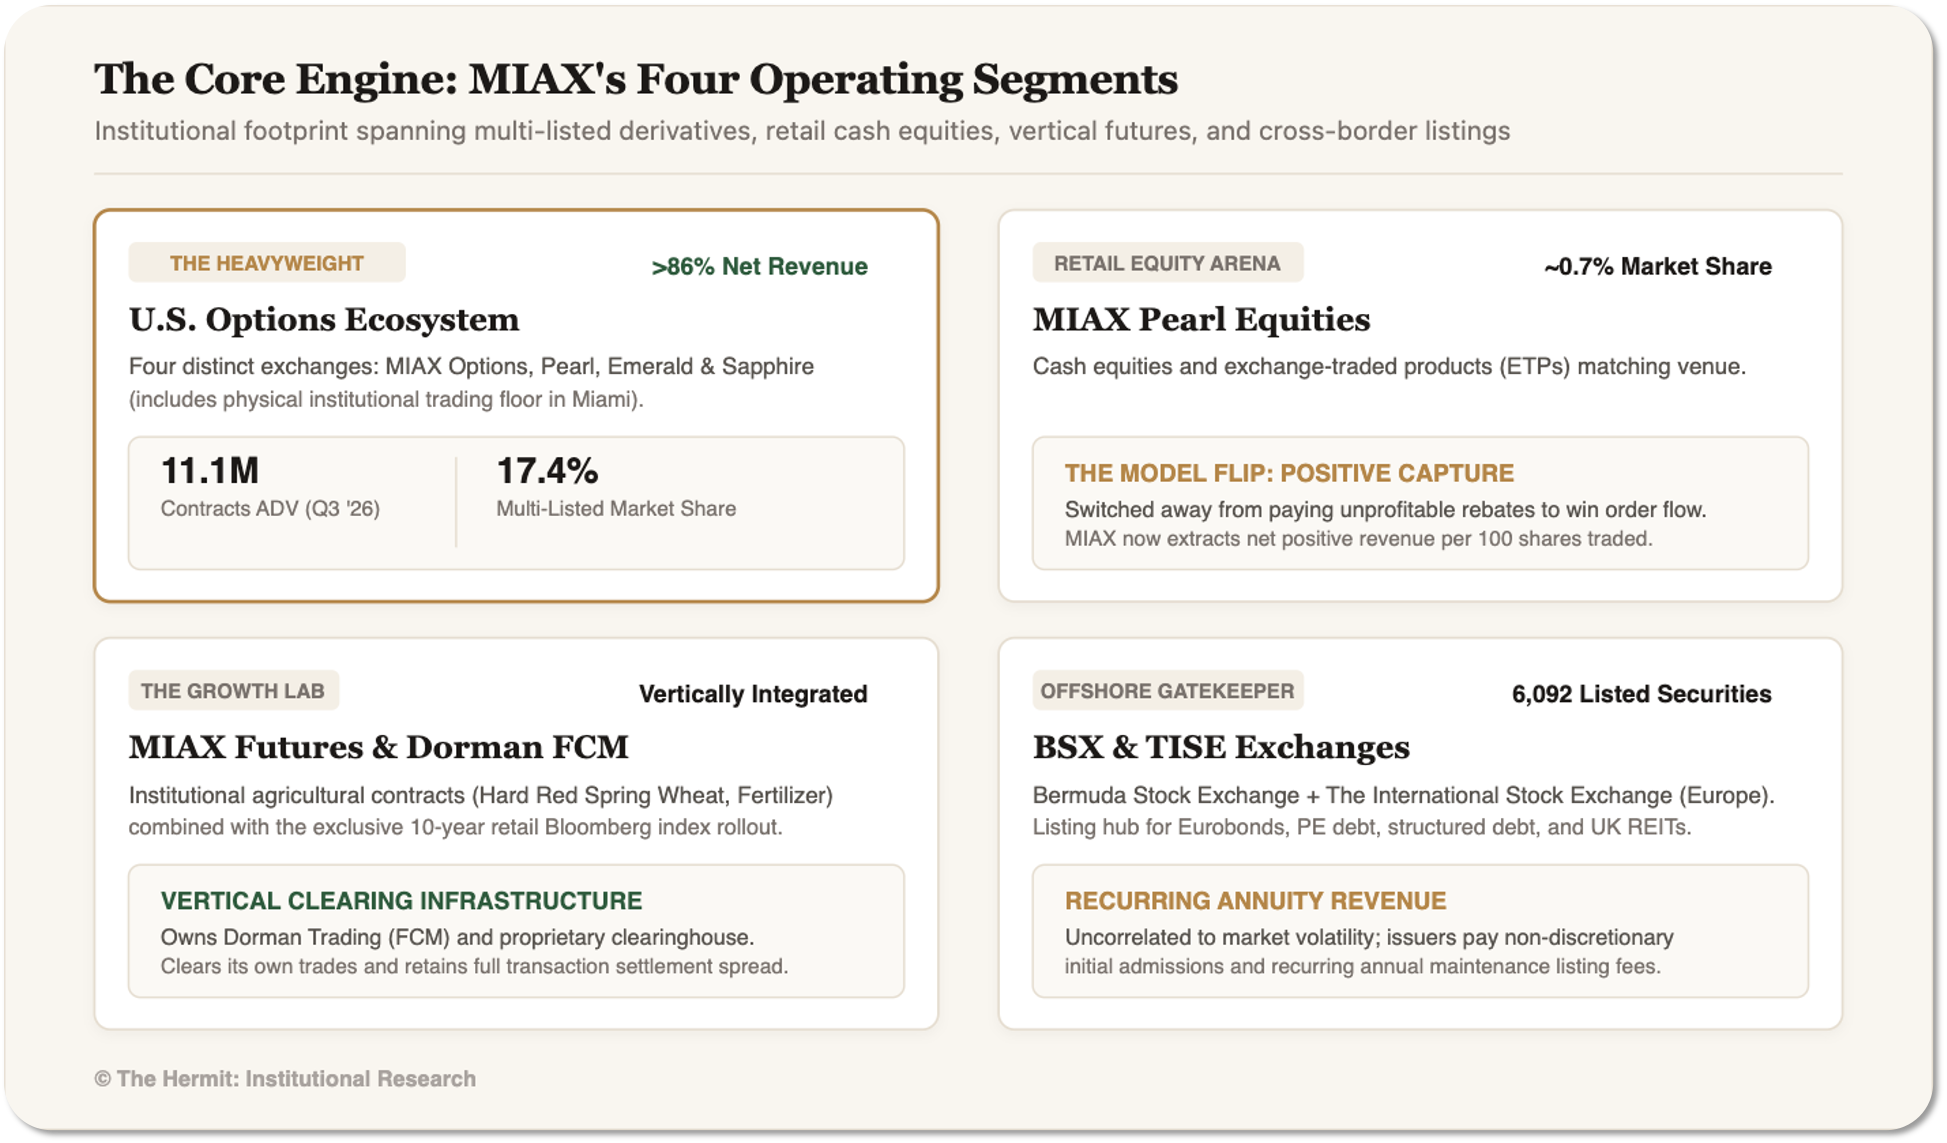
The Cash Machine
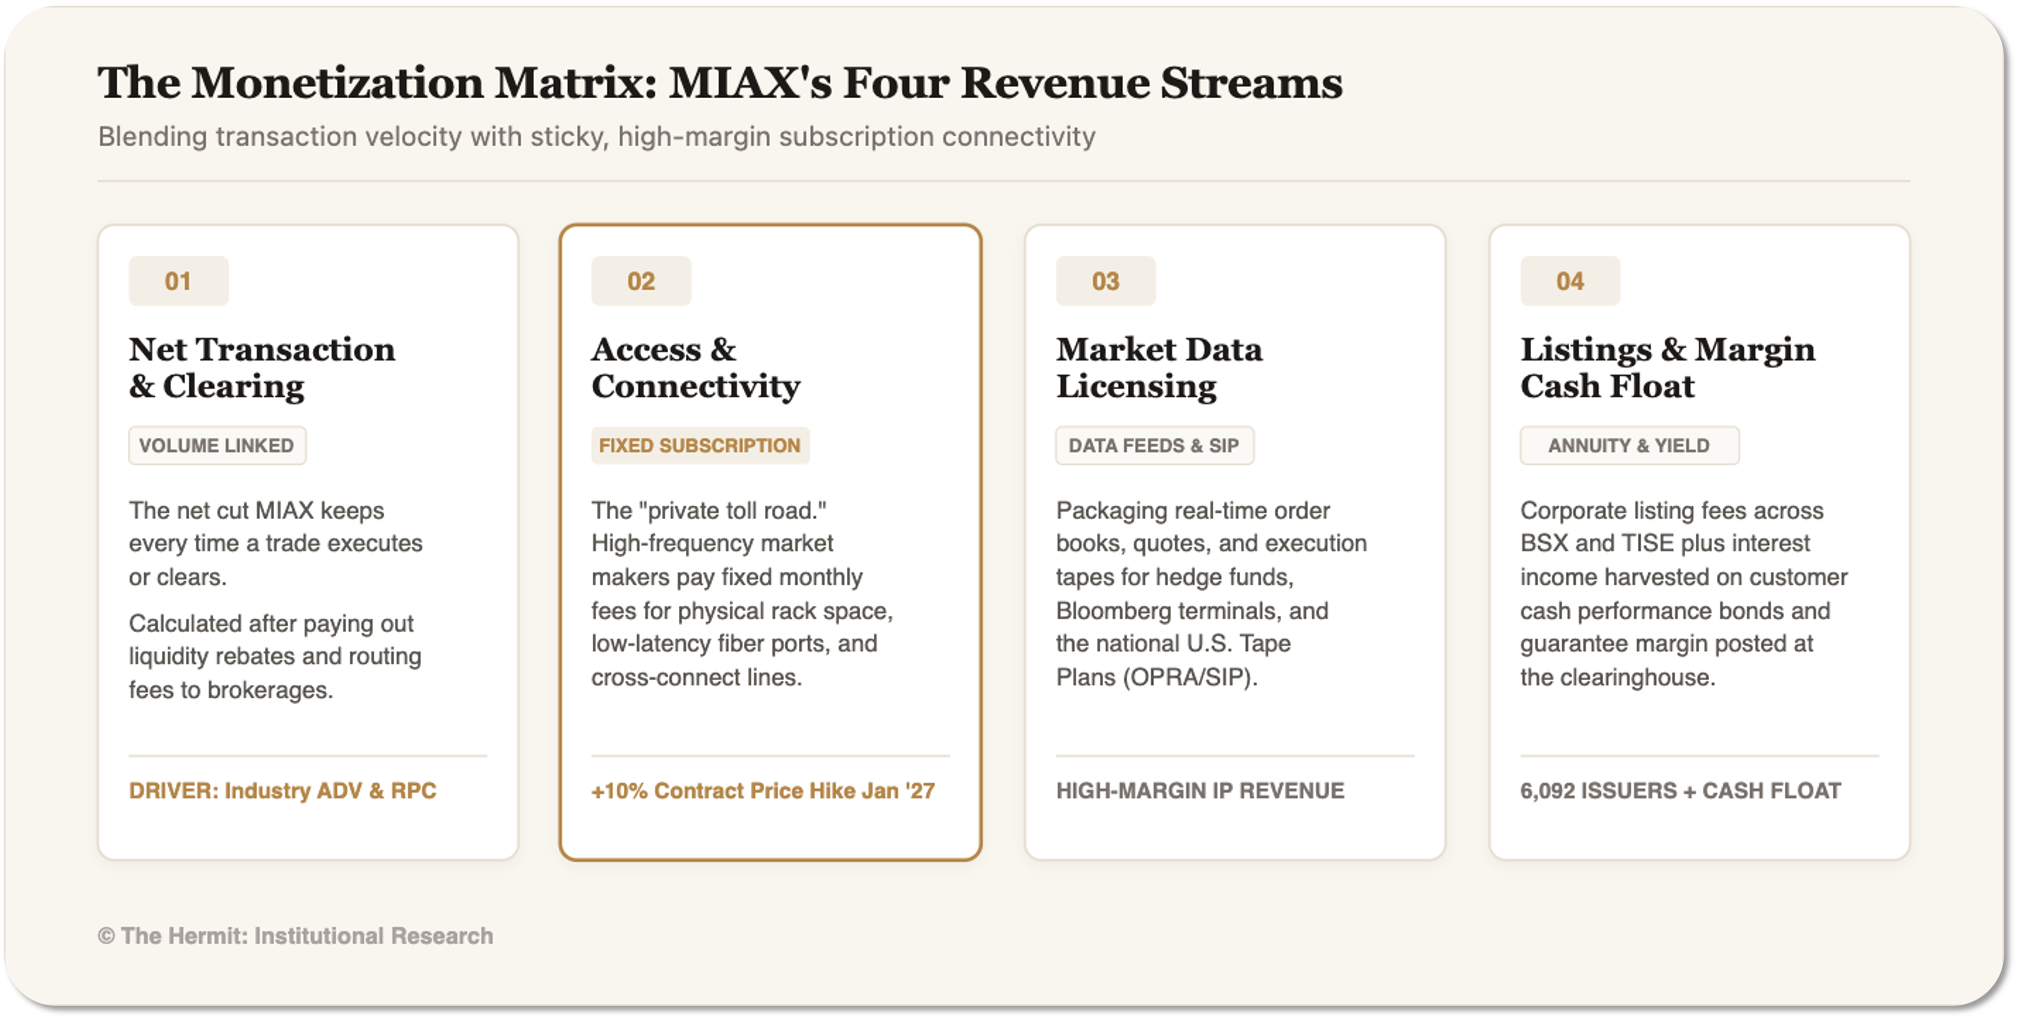
The Perfect Combination of Moat and Operating Leverage
Do not forget, MIAX owns its technology platform end-to-end.
Their network operates at 36 microseconds of latency with 99.999% uptime.
Because the software and infrastructure costs are largely fixed, almost every new dollar of trading volume drops straight to the bottom. In Q3 2026, MIAX produced an Adjusted EBITDA margin of 54%, and we should see that increase over time.
For additional context on how exchanges work and a closer look at the Big 6, we broke every detail of their mechanics and tech down in our last portfolio update:

🎯 Catalysts: Why Now?
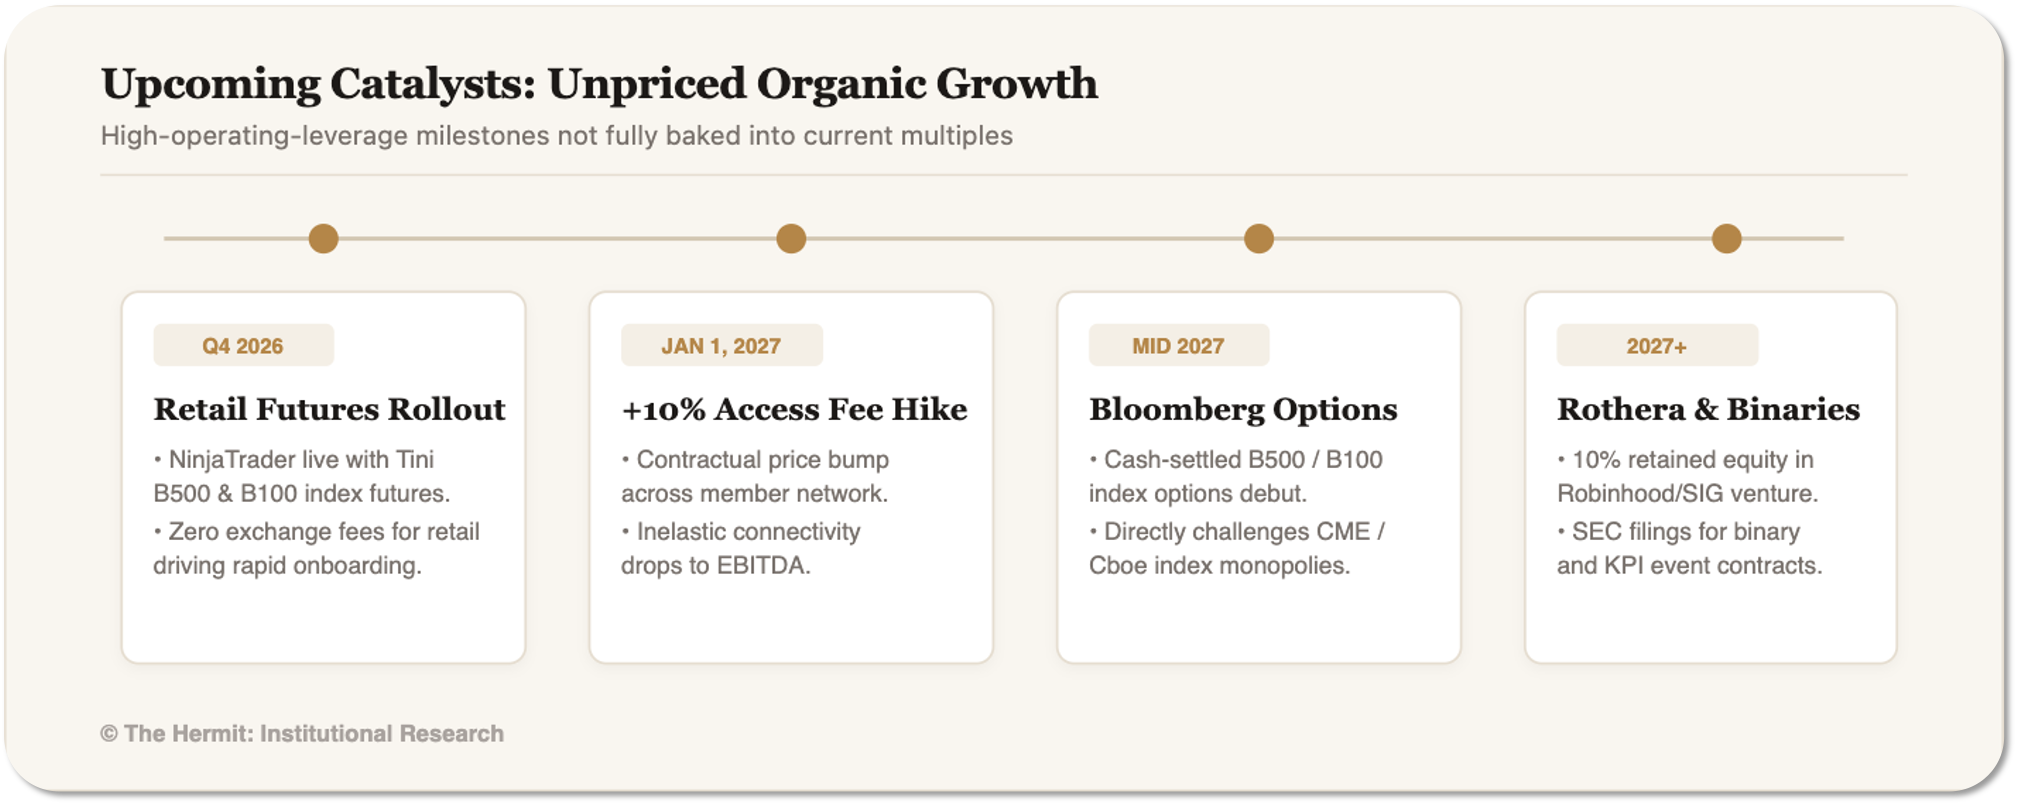
MIAX has several tangible growth drivers ready to hit the tape over the next 12 to 24 months.
The 10-Year Exclusive Bloomberg Partnership (Disrupting the CME):
MIAX holds an exclusive license to list futures and options on Bloomberg’s flagship indexes (B500 and B100) across North and South America.
They launched Tini B500 and Tini B100 futures specifically sized for retail traders with zero exchange fees and free market data.
After onboarding NinjaTrader in mid-October 2026, multiple new retail brokerages are going live in Q4 2026. In 2027, MIAX will launch B500 and B100 index options and options on futures.
Contractual 10% Access Fee Increase (Jan 1, 2027):
Management confirmed an across-the-board ~10% bump in exchange access fees starting January 1, 2027. Because exchange connectivity is sticky (trading firms cannot simply unplug), this is basically pure new orders plus all last year’s cash flow times 1.10.
Physical Floor Expansion at MIAX Sapphire:
The newly launched Miami Sapphire floor captured 12.4% of total U.S. floor-traded options volume in Q3 2026. Floor volume attracts complex, large-block institutional trades that cannot be fully matched on pure electronic books.
SEC Filings for Cash-Settled Binary & Event-Based Options:
MIAX is preparing SEC filings to launch cash-settled binary index options (tied to Bloomberg indexes) and binary KPI options.
This positions them to compete in outcome-based and prediction-style retail trading under a regulated framework.
10% Retained Stake in Rothera (Robinhood & Susquehanna JV):
MIAX sold 90% of LedgerX (MIAXdx) to a Robinhood/SIG joint venture (Rothera) while retaining a 10% equity stake.
If Robinhood’s user base explodes into prediction and crypto derivative markets, MIAX owns a direct call option on that success. Zero balance sheet risk on this one.
Pristine Balance Sheet Firepower:
MIAX has virtually no debt ($1.5m maturing in December 2026) and $698.9m in cash and cash equivalents.
They have an enormous cash runway for capital returns, or aggressive product incentive programs. Hopefully this will not lead to a lot of M&A activity.
💰 What’s It Worth?
A Quick Note Before We Break Down Numbers: If you aren’t a paid subscriber yet, consider joining us.
We publish high-conviction research twice a week for just $30/year (the Substack minimum), mostly as a speed bump to keep AI scrapers from draining our work for free.
We want our research accessible, but real value goes both ways.
If you just joined, check our welcome email for links to exclusive bonus content. Thanks!
As always, let’s start by breaking down the assumption. In this case, we could go lower, but to reflect the current risk and return expectations, we used a 9.5% discount rate (WACC), built from a 4.2% risk-free rate, a beta of 1.00, and a 5.3% equity risk premium.
Beyond the explicit five-year window, we assume MIAX’s cash flow will grow at a steady 3.0% annually forever.
Arguably, we could use a much lower WACC, as the company has a substantial amount of cash and, more importantly, is a direct peer to organizations like NASDAQ and CBOE. It’s a freaking tollbooth.
Base Case [$41.95] (+22% Upside)
The company enters this projection period on exceptionally solid financial footing, carrying an annualized 2026 net revenue of about $535m, virtually no debt ($1.5m), and a hefty cash balance of $698.9m.
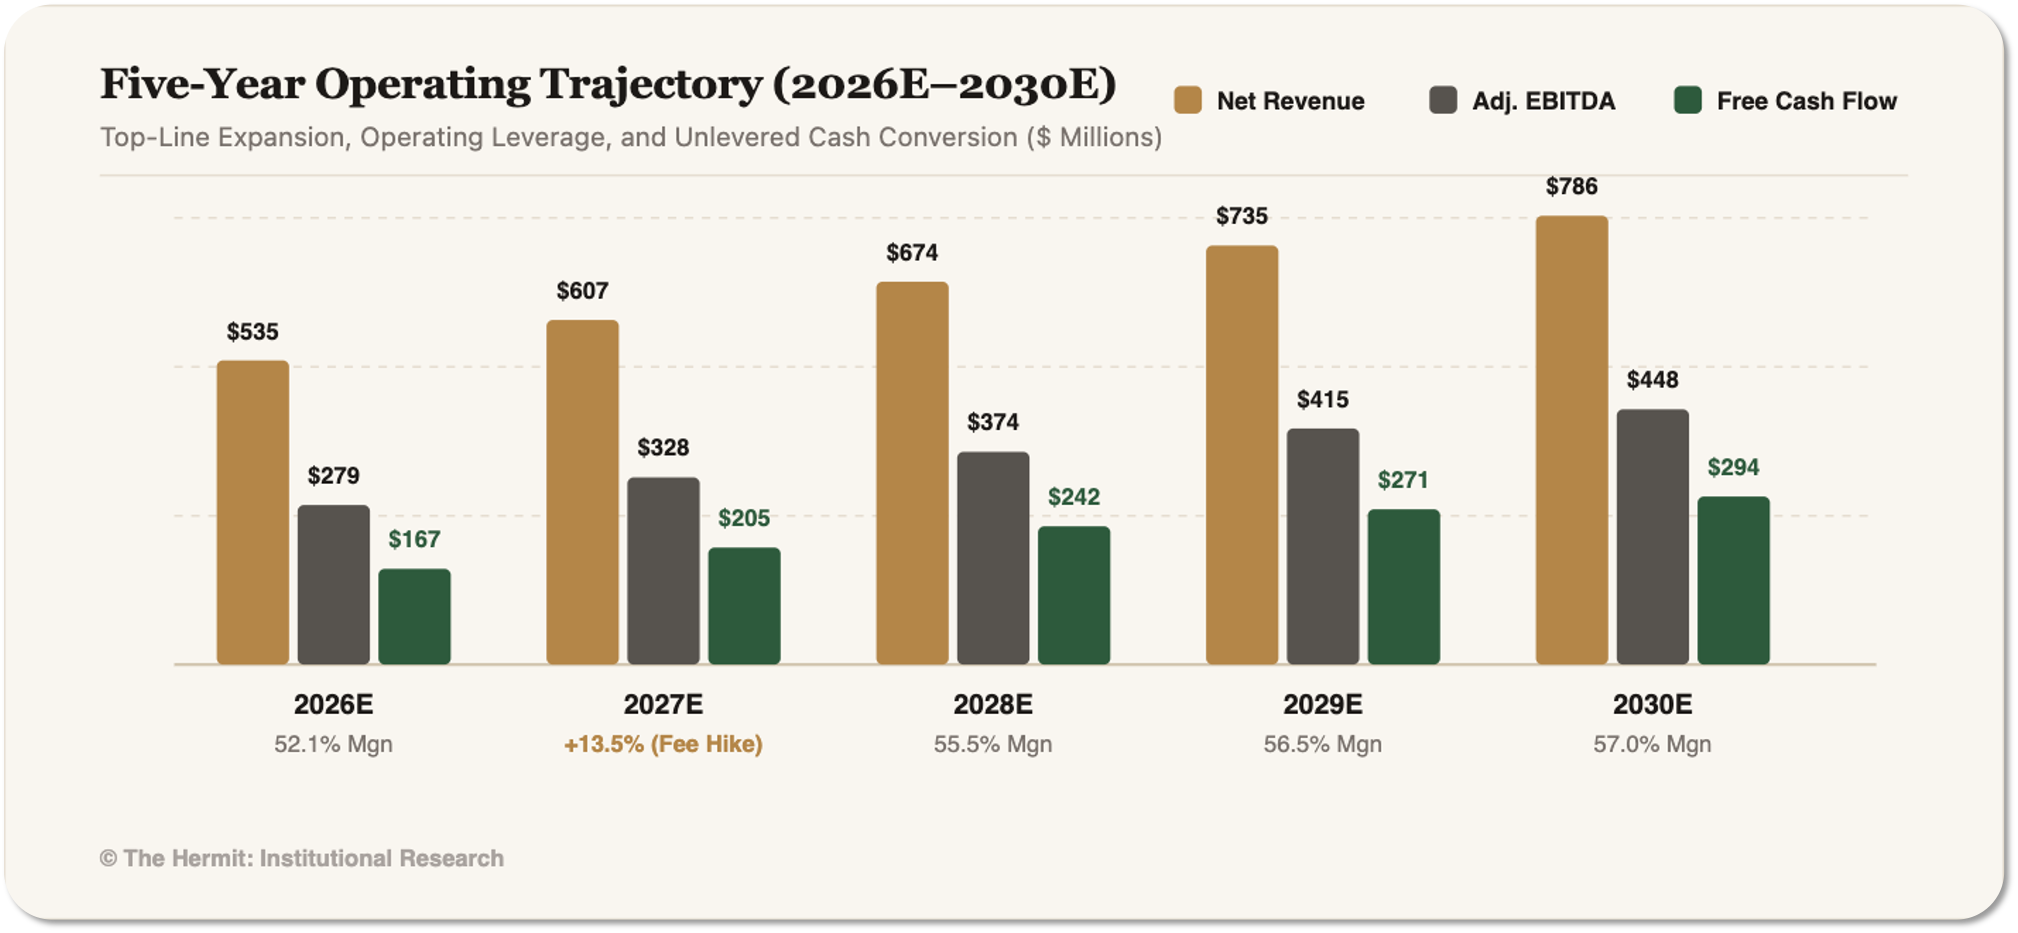
Looking at the five-year forecast, MIAX’s revenue is set to accelerate by 13.5% in 2027, driven by new Bloomberg index product rollouts and an upcoming 10% hike in exchange access fees, before gradually normalizing to a sustainable 7.0% growth rate by 2030.
As (net) revenue expands from $535.0m to $786.1m against a largely fixed operating costs, margins should widen, with adjusted EBITDA climbing from $279.0m (a 52.1% margin) to $448.1m (a 57.0% margin).
After accounting for steady capex and software investments of around $40m-$45m a year, roughly 27% in taxes, and modest WK needs…. we should see annual (unlevered) FCF expand from $167.2m in 2026 to $294.1m by 2030.
Discounting the remaining fourth quarter of 2026 and each subsequent year back to PV gives us $823.3m worth of cumulative FCF.
Terminal value is about $4,660.3m, which, netted back to PV, is $3,169.0m.
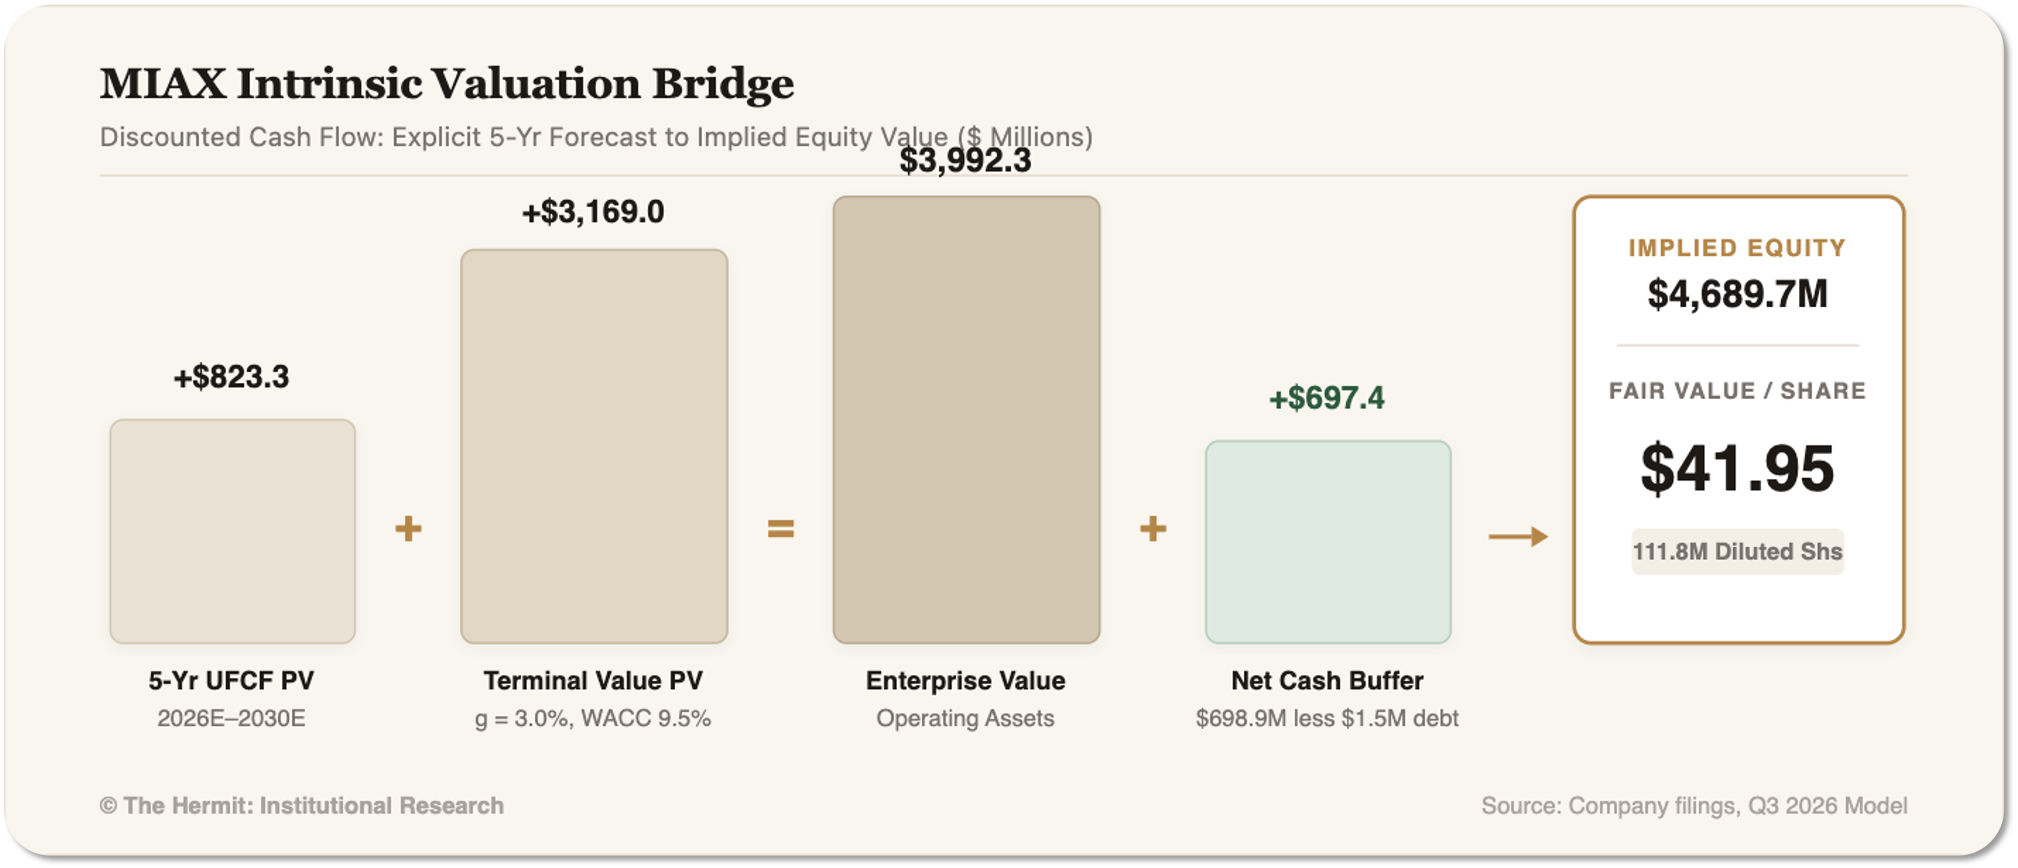
Combining all of this gives us an enterprise value of approximately $3,992.3m, and once you add back the net cash worth $697.4m, you get to an implied equity value to $4,689.7m.
Spread across 111.8m fully diluted shares, that’s an intrinsic fair value of $41.95 per share.
Although the valuation of this company is not exactly a ten-bagger, or anything of the sort, the items that we described as either happening soon but still under development (Bloomberg futures) or highly lucrative call options (Robinhood prediction markets) would substantially boost what is already a fantastic business with a very capable management team.
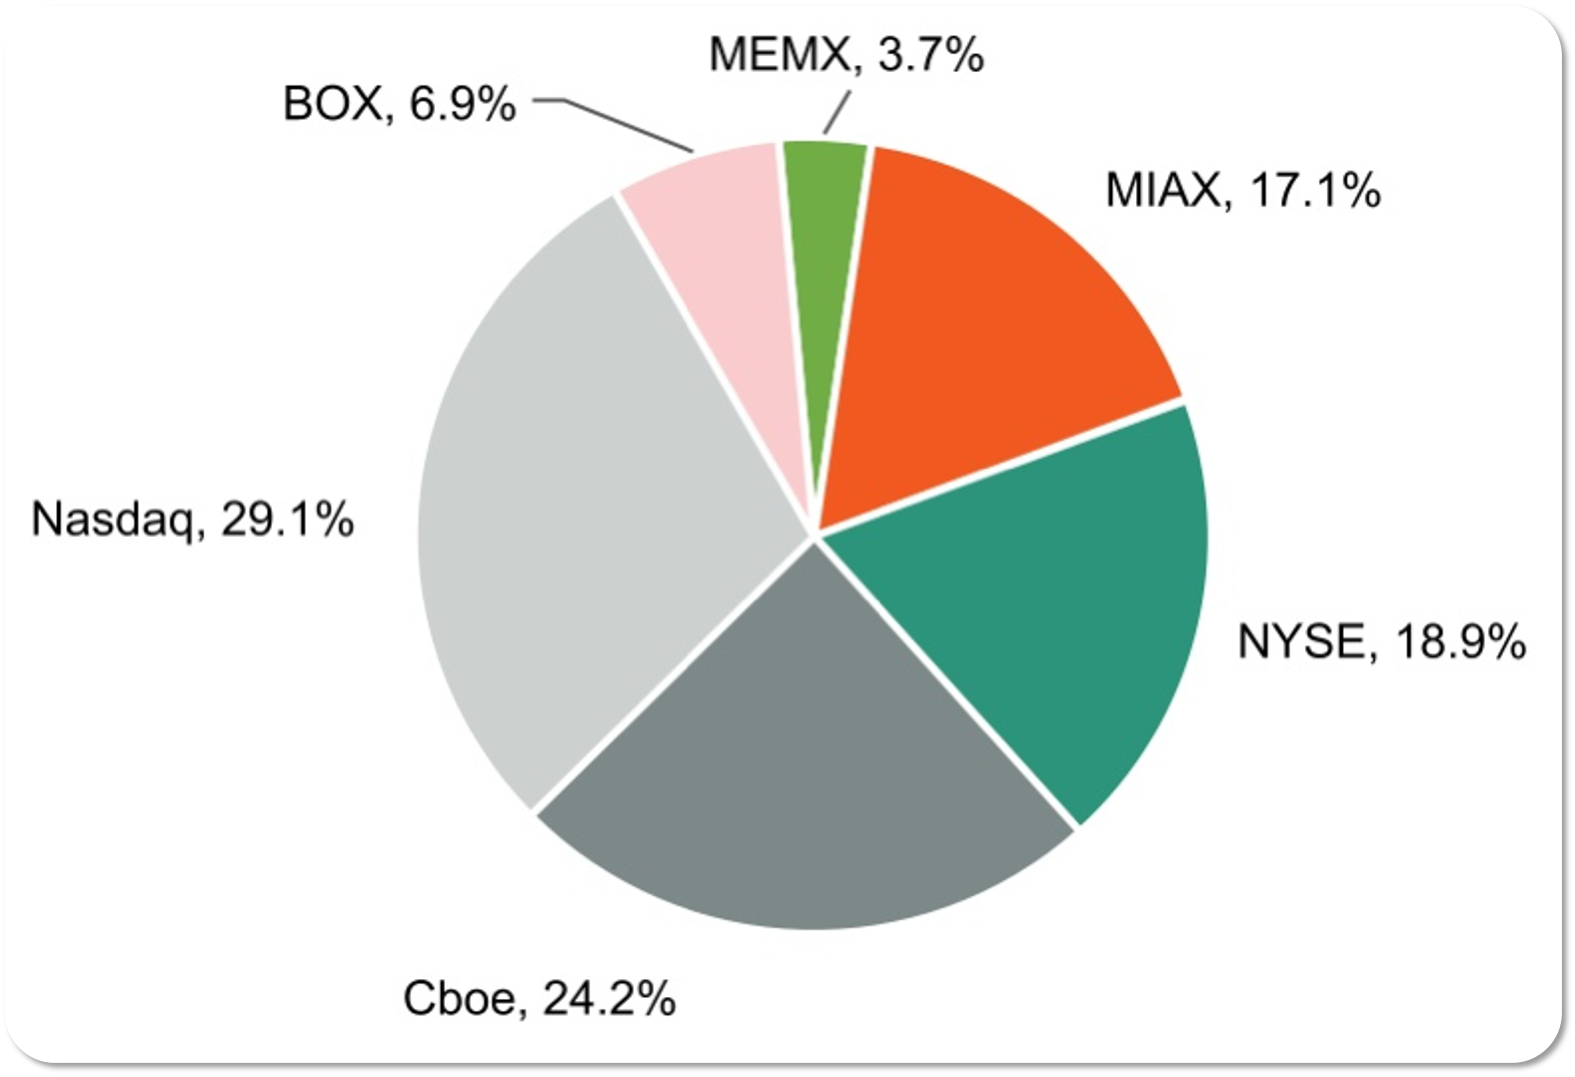
These guys are a freaking exchange that’s grown from nothing to having a 17%+ share of a market that’s growing at double digits every year.
Unlike most of the companies we share which have a one-and-done catalyst, where once the catalyst is gone you simply exit, this company right here feels like the definition of a buy and hold forever.
As a tollbooth, it’s also highly unlikely that this type of business sees a lot of downside.
It should be a stable, staircase-like ascent to the heavens.
Please don’t quote me on this last part… I’ve been listening to too much Led Zepellin.
Sensitivity Analysis
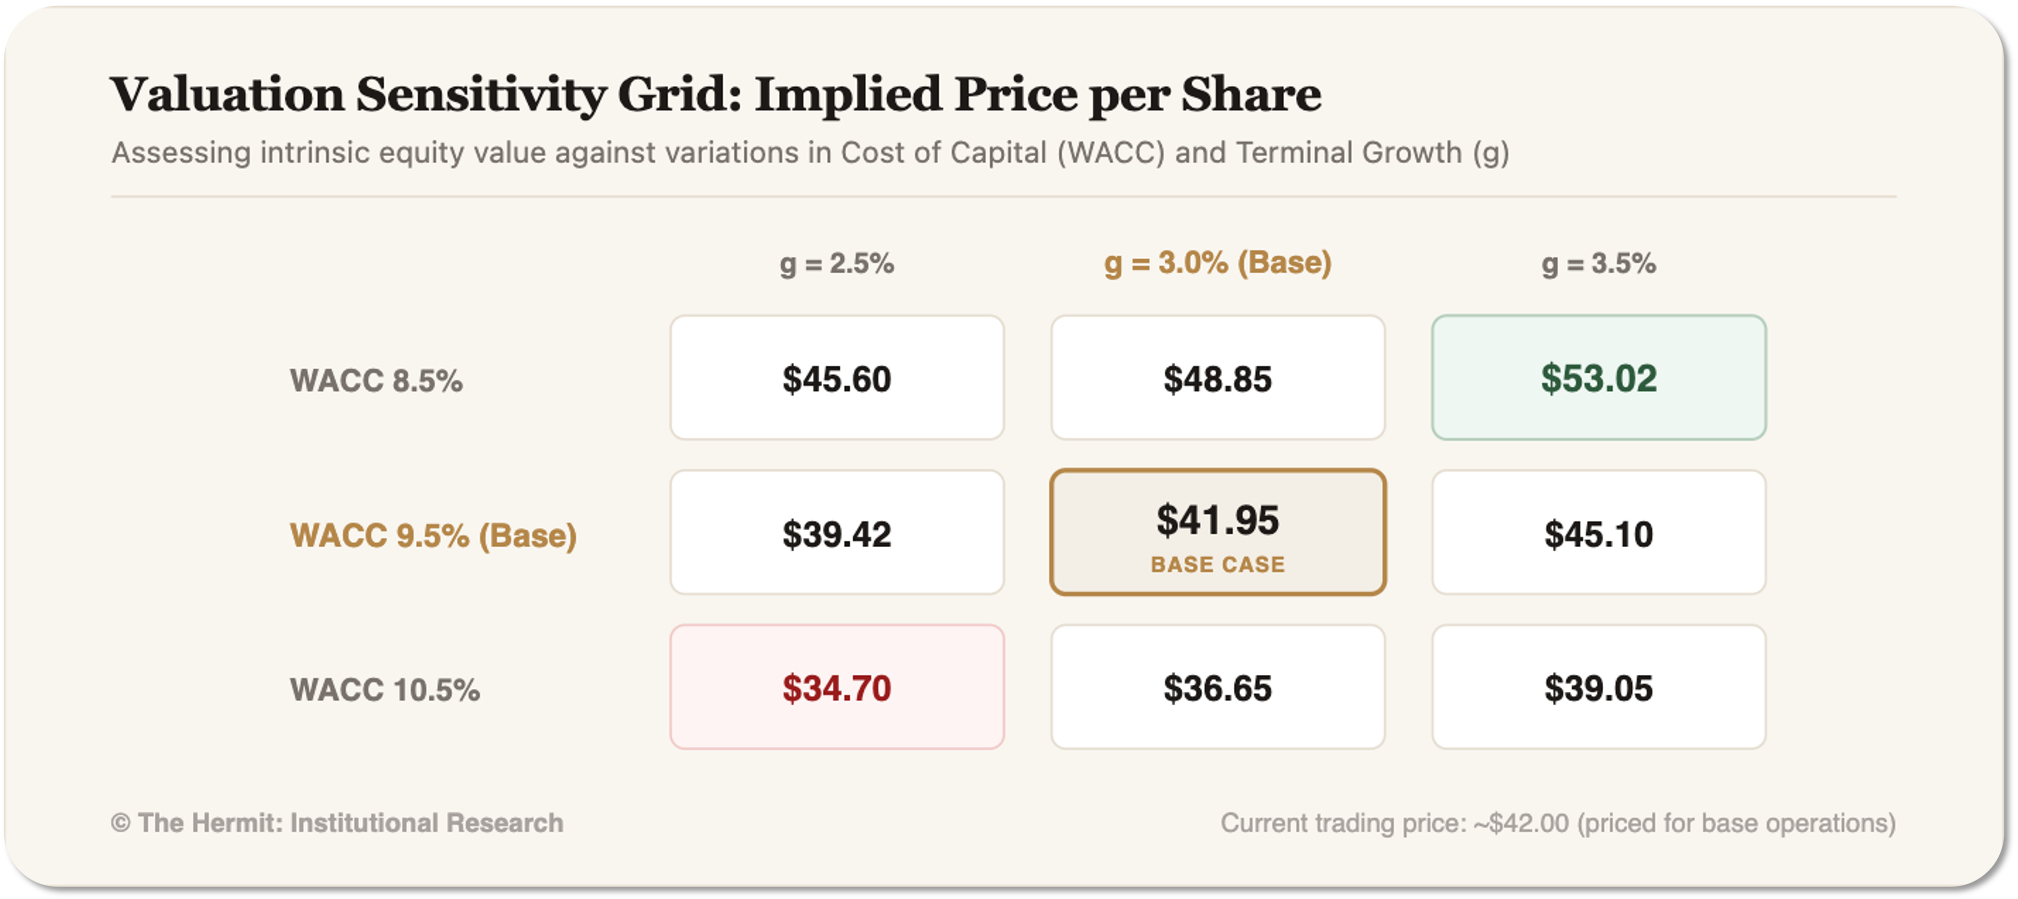
As a final note and to best understand the valuation, we added a sensitivity table that visually illustrates where the market is pricing the company today. It also highlights how a 7.0% or 7.5% implied WACC, which is much closer to how one could value this business, would significantly boost the valuation.
In our view, every single catalyst on the list, once executed, should boost the valuation by $5–$10 per share instantly.
Super useful, thanks for opening up this one