

Want more context? Track the journey so far here.

Index
1. Executive Summary & Asset Allocation
1.1.- Public Equities: Detailed YTD Performance, Asset Allocation, and Holdings Overview
1.2.- Private Assets: Coffee Business Unit Economics Breakdown
2. October Review
2.1.- Macro Context and Market Observations
2.2.- Navigating the Big 6 Options Markets
2.3.- Cash & Treasury Compartment: % Remuneration Breakdown & FX Push
2.4.- ETF Compartment: Broad Index and Emerging/Frontier Markets
2.5.- Opportunistic Compartment: Reviewing Exits and Improved Goals
3. Holdings & Portfolio Activity
3.1.- Position Sizing, Entries and Exits
3.2.- Earnings Releases, Upcoming Catalysts, Insights and Updates
Briefing
This 29th edition was just too much fun. We did a lot of digging on the public side on three major topics: market makers (especially for options), Chinese low-cost producers, and North American high-quality food distributors.
We’ve included a comprehensive review of the big six US options exchanges, digging into routing mechanisms, internal order-matching engines, maker-taker fee models, and which players are winning market share.
It was definitely one of our most intense preparations, given that we are now set to spend about three weeks traveling across Eastern China to visit a handful of companies, look at their business models from the factory floor, and assess how we want to proceed there.
On the private side, there were a lot of moving pieces. We will be breaking down the unit economics of the coffee business live with a high degree of precision, and show you major developments on both the revenue and cost sides of the equation.
Back on public equities, October and November are a great time to be a full-time investor. Everyone is reporting earnings and, crucially for us, once earnings are out, management teams are liberated from quiet periods and can sit down with us.
The next few weeks are packed with 1-on-1 interviews with both leadership at our portfolio companies and their competitors. All of these should provide a ton of useful context to shape conviction. We’ll include insights from the earnings calls in this write-up, along with our rationale behind recent buys, exits, and position sizing.
On the mistakes front, this month saw way too much activity, with 44 trades executed versus 32 in September and 19 in August. We want to bring that number as close to zero as possible, so we are putting up strict guardrails to curb overtrading via strict weekend revisions.
Note: Even though the trade count is high, they only involve a dozen companies. e.g. Omni represented 3 trades during the month.
In terms of portfolio concentration, we peaked at 22 individual names. After careful reflection, we trimmed that down to 18 positions by month-end, and expect to be at 16 by the end of November.
We’ve laid out clearly why two of our current holdings no longer make sense. We only want the best of the best, and when the original thesis weakens, we must take decisive action. Monitoring existing ideas is almost always more important than generating new ones. A great investor simply doesn’t have dozens of exceptional ideas, nor can anyone process infinite noise.
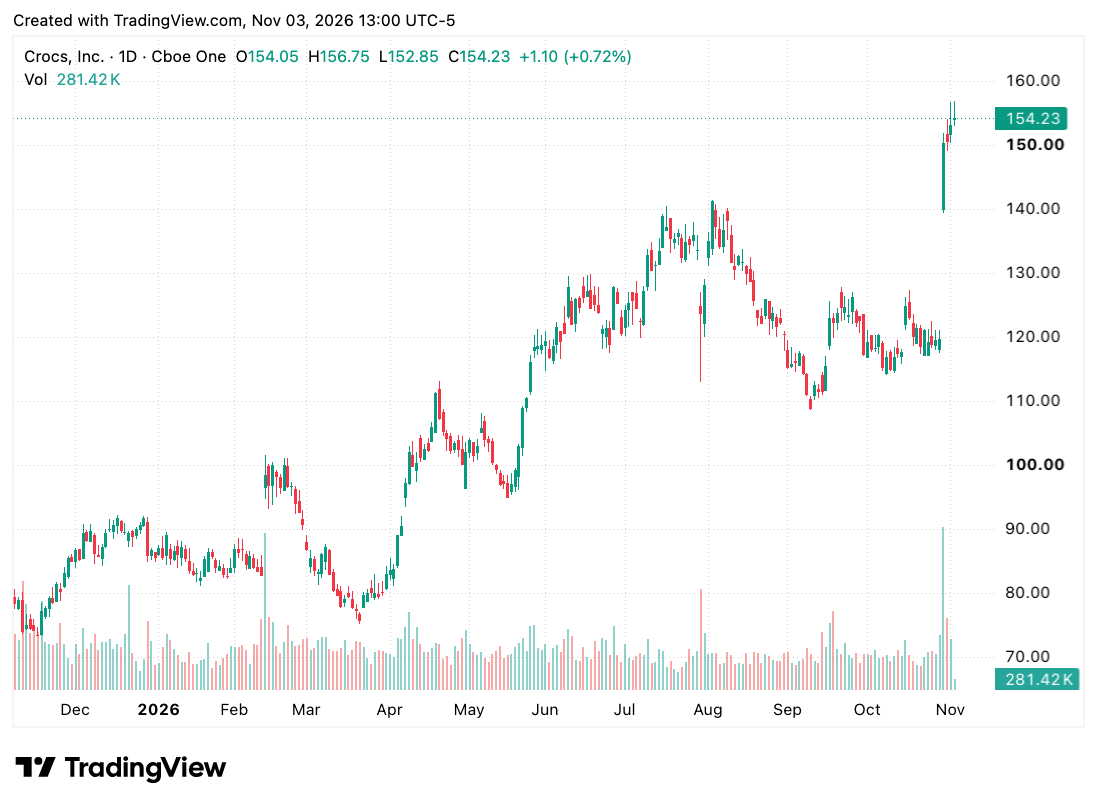
We’re sticking to the high-conviction names that offer 3x–10x upside with concrete catalysts over the next 12 to 18 months.
Simple in theory, but hard as hell in practice.
This publication is confidential and intended solely for the use of the person or entity to whom it is given or sent. It may not be reproduced, distributed, or transmitted without the author’s prior written consent.
By accepting to receive the full post as a 🧙♂️ Inner Circle member, the recipient agrees to be bound by the foregoing limitations.
None of the following should be construed as investment advice. Please consult a financial advisor before making any investment decision. You will find a full disclaimer at the end of this post.

📊 Portfolio Overview
Returns (Asset-Weighted)
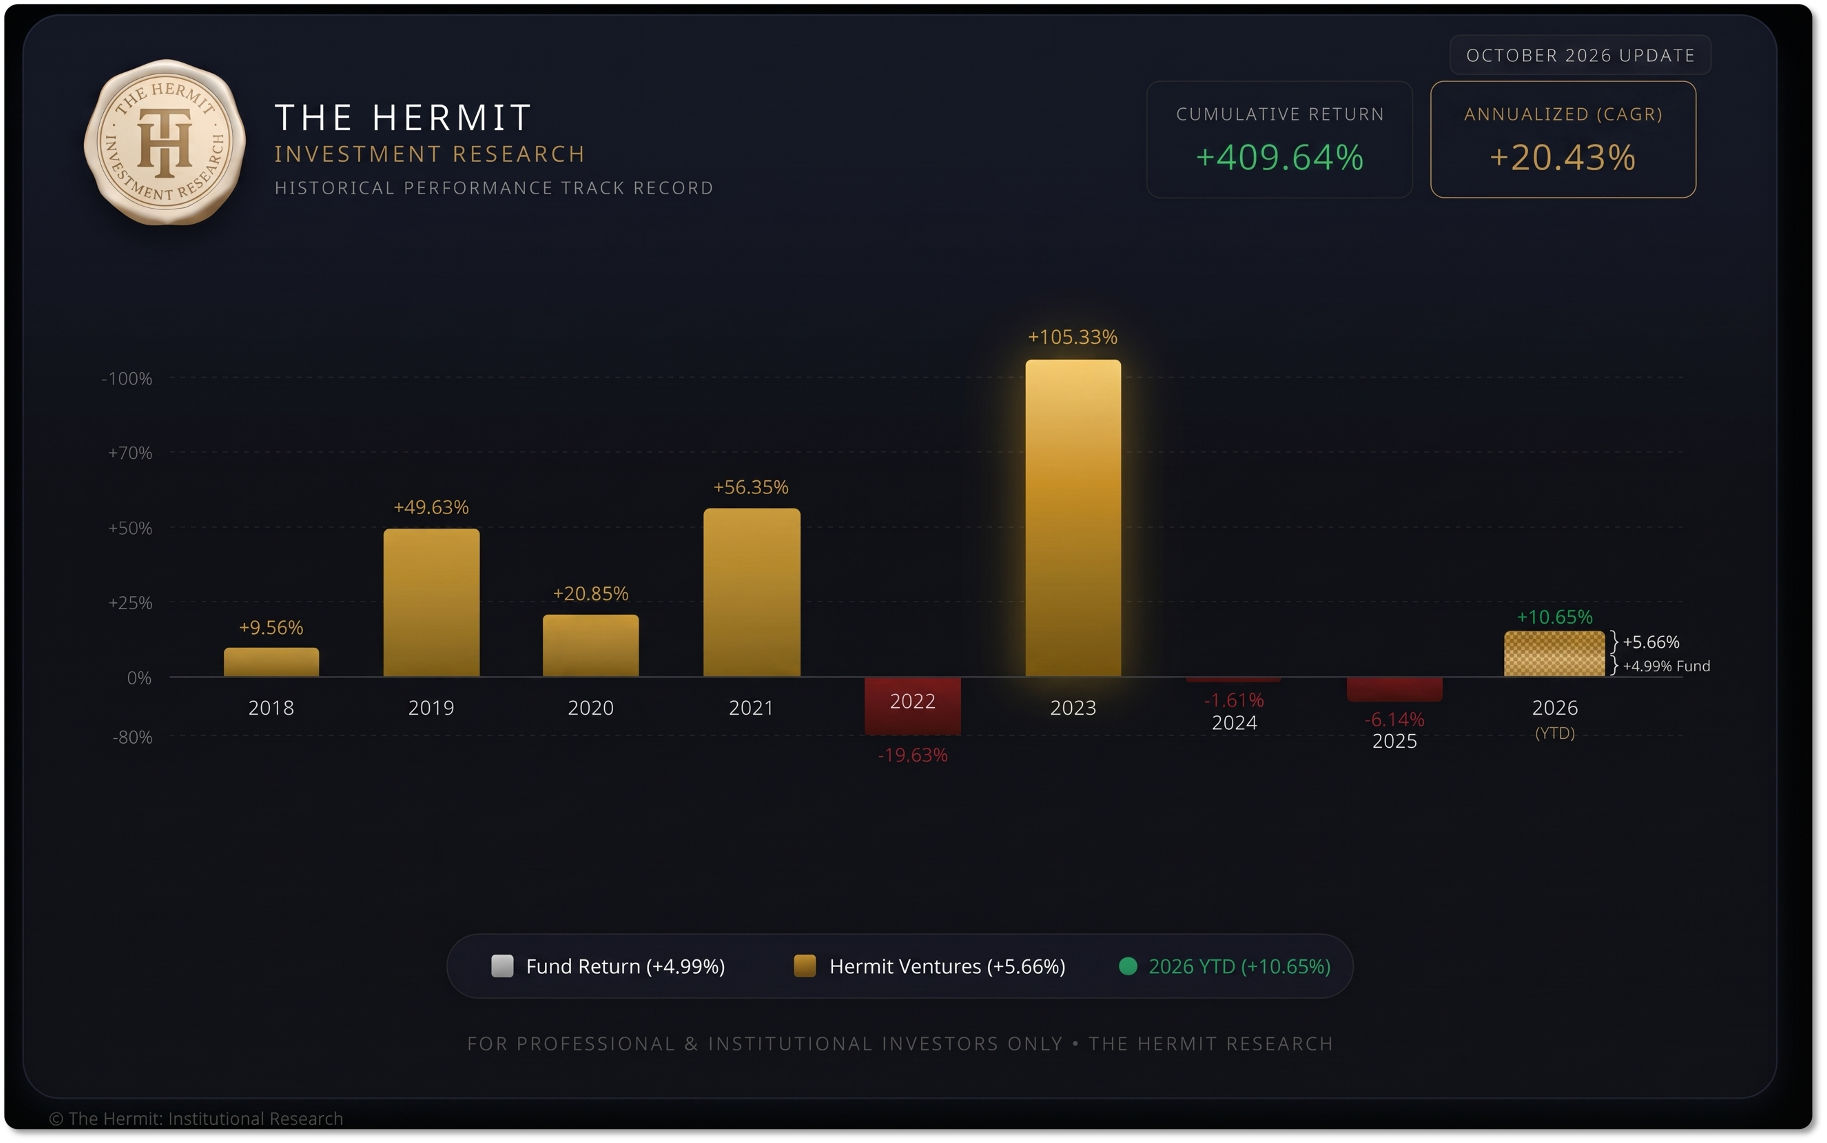
Public Market Portfolio
Throughout the month, we purchased shares in these new names: