

Want more context? Track the journey so far here.

Index
1. Executive Summary & Asset Allocation
1.1.- Public Equities: Detailed YTD Performance, Asset Allocation, and Holdings Overview
1.2.- Private Assets: Business Development Update [Disclosing Details]
2. Q3 Review
2.1.- Quantitative Evaluation: YoY Performance Metrics, Sizing, Concentration, Winner/Loser Spread, and Cash Transition
2.2.- Qualitative Evaluation: Objectives Assessment, What Worked vs. What Didn’t, Behavioral Biases, and Philosophy Adjustments
3. September Review
3.1.- Macro Context and Market Observations
3.2.- On Chinese Monetary Policy and Gold Hoarding
3.3.- Cash & Treasury Compartment: % Remuneration Breakdown & FX Push
3.4.- ETF Compartment: Broad Index and Emerging/Frontier Markets
3.5.- Opportunistic Compartment: Individual Names and Goals
4. Holdings & Portfolio Activity
4.1.- Position Sizing, Entries and Exits
4.2.- Earnings Releases, Upcoming Catalysts, Insights and Updates
Briefing
This 28th edition is a massive one, and we’ve been working on it for a while. We are finally disclosing our private project, laying out the hard numbers alongside how operations are materializing.
Naturally, because good due diligence requires proper fuel, we have also sprinkled in a few serious specialty coffee pointers along the way.
The heart of this letter pulls together several high-stakes threads across our investable universe. Among the newest bits, we’ll break down how we’ve been building out a position (still incomplete) in a major O&G hardware manufacturer, splitting the OpCo from the FinCo to understand what is really going on.
From there, we pivot directly into the legal trenches of Eastern Europe, walking through the critical Ukrainian asset dispute heading straight toward a pivotal ruling on October 12th. Classic case of using a 28%+ WACC to discount dubious production.
Then comes one of the most intriguing valuation anomalies on our desk: a specialized data management firm that would terrify a traditional screener because of its extreme reliance on a single customer. Dig a layer deeper, though, and you find a business minting money with 20% FCF margins while running at 40% capacity.
We round out the entire letter with our classic quarterly retrospective, walking through every single position on our books to check in on thesis tracking, risk management, and the near-future catalysts lined up on the horizon.
Please do not skip the conclusion. We left an essential note at the end detailing how our structure and capital deployment will pivot if that potential merger crosses the finish line.
Inner Circle community, you know exactly what deal we’re referring to… strictly between us for now, of course.
For the Inner Circle members
Your invitation to our live quarterly review is waiting below.
We will dissect the individual holdings and themes for the upcoming quarter. We think the value is in having an open room to tackle all of your questions head-on. Make sure to jump in live, but if you can’t make the slot, the full recording will be up shortly after.
So just shoot us your questions via DM, leave a comment at the end of this post, or email us beforehand so we can address everything on the call.
This publication is confidential and intended solely for the use of the person or entity to whom it is given or sent. It may not be reproduced, distributed, or transmitted without the author’s prior written consent.
By accepting to receive the full post as a 🧙♂️ Inner Circle member, the recipient agrees to be bound by the foregoing limitations.
None of the following should be construed as investment advice. Please consult a financial advisor before making any investment decision. You will find a full disclaimer at the end of this post.

📊 Portfolio Overview
Returns (Asset-Weighted)
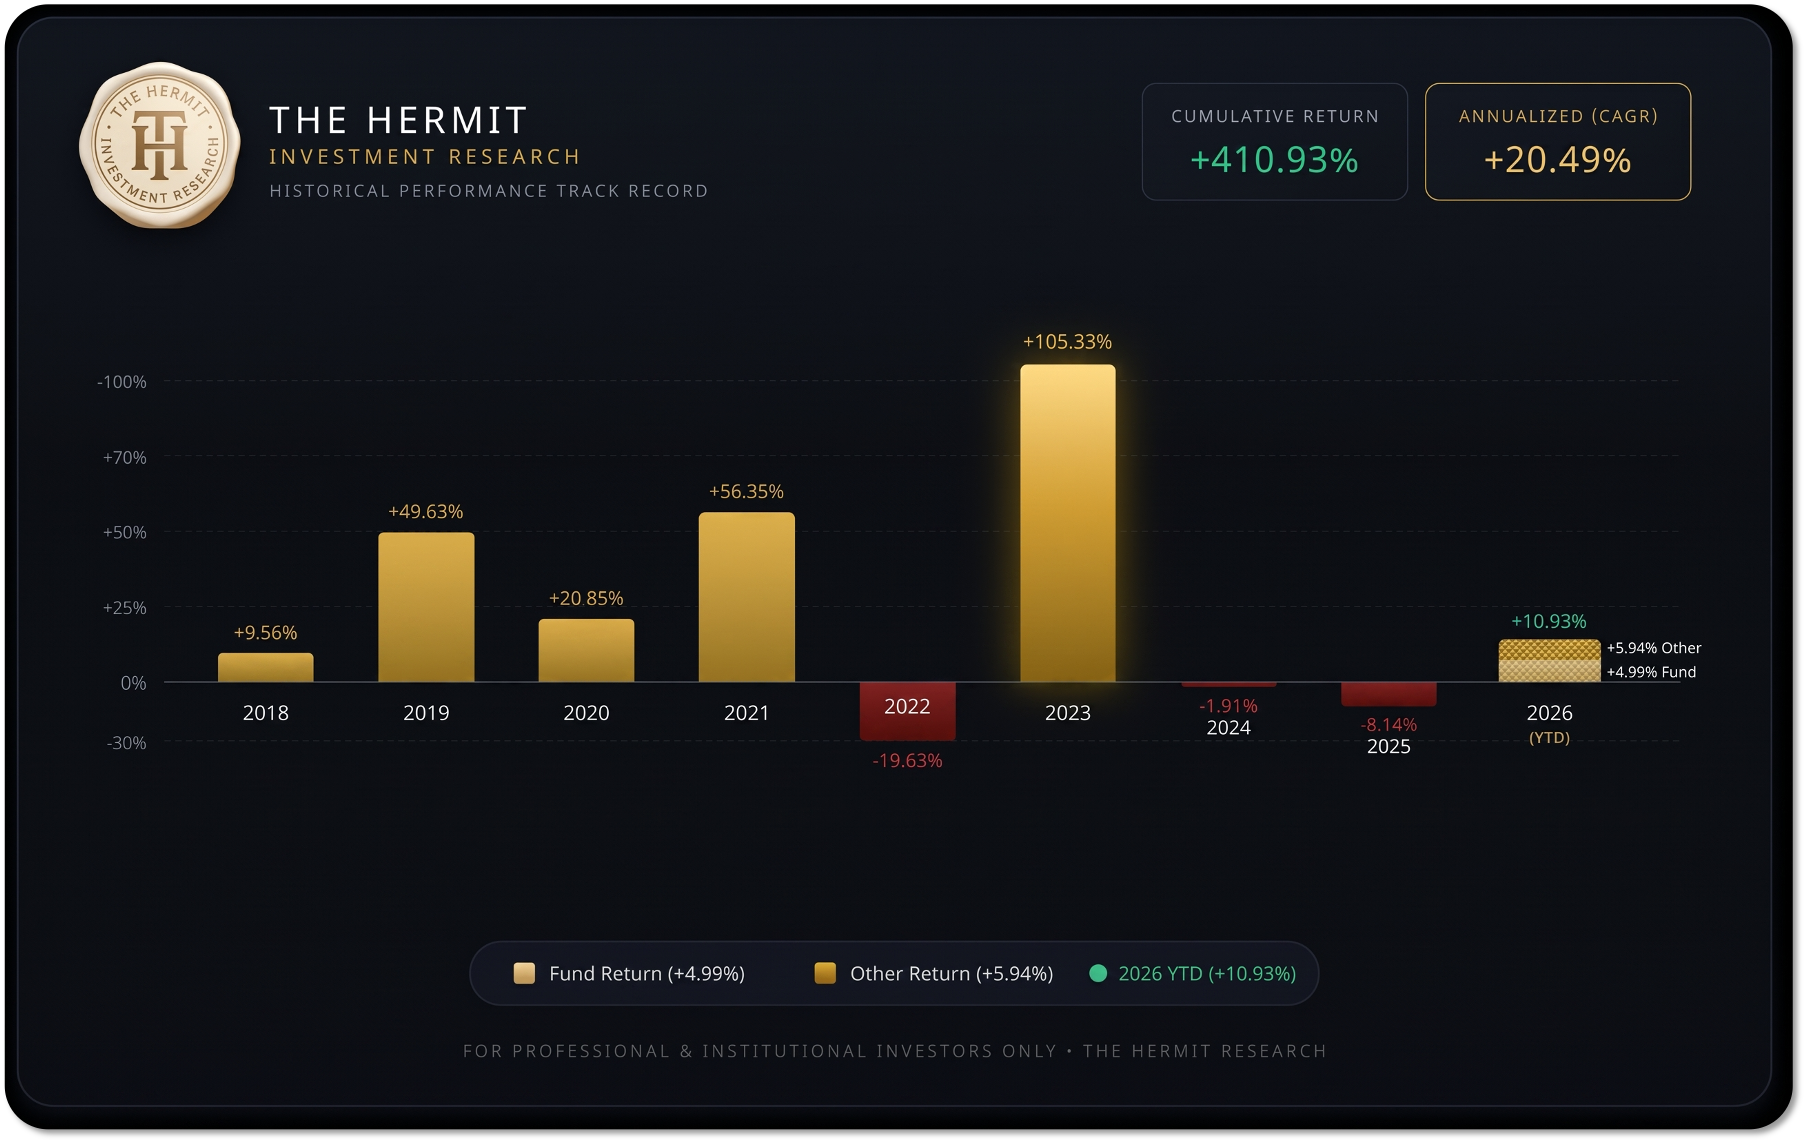
Public Market Portfolio
Throughout the month, we purchased shares in a few individual names, including: