

We usually release these PoW posts on Saturdays, but we’re waiting on management to give us the green light to quote them directly in our next, and probably best, long-form write-up to date.
That adds a ton of value to the piece, so... definitely worth the wait.
This piece is brought to you by Baseline.
Use code HERMIT for 20% off
Let’s use some Buffett-esque language. Imagine coming across a business that the market has priced like a cigar butt, even though it operates more like a tollbooth on the world’s most lucrative energy basins.
Cue the dramatic tension music, dim the studio lights, and zoom in tight on the hot seat.
Final answer?
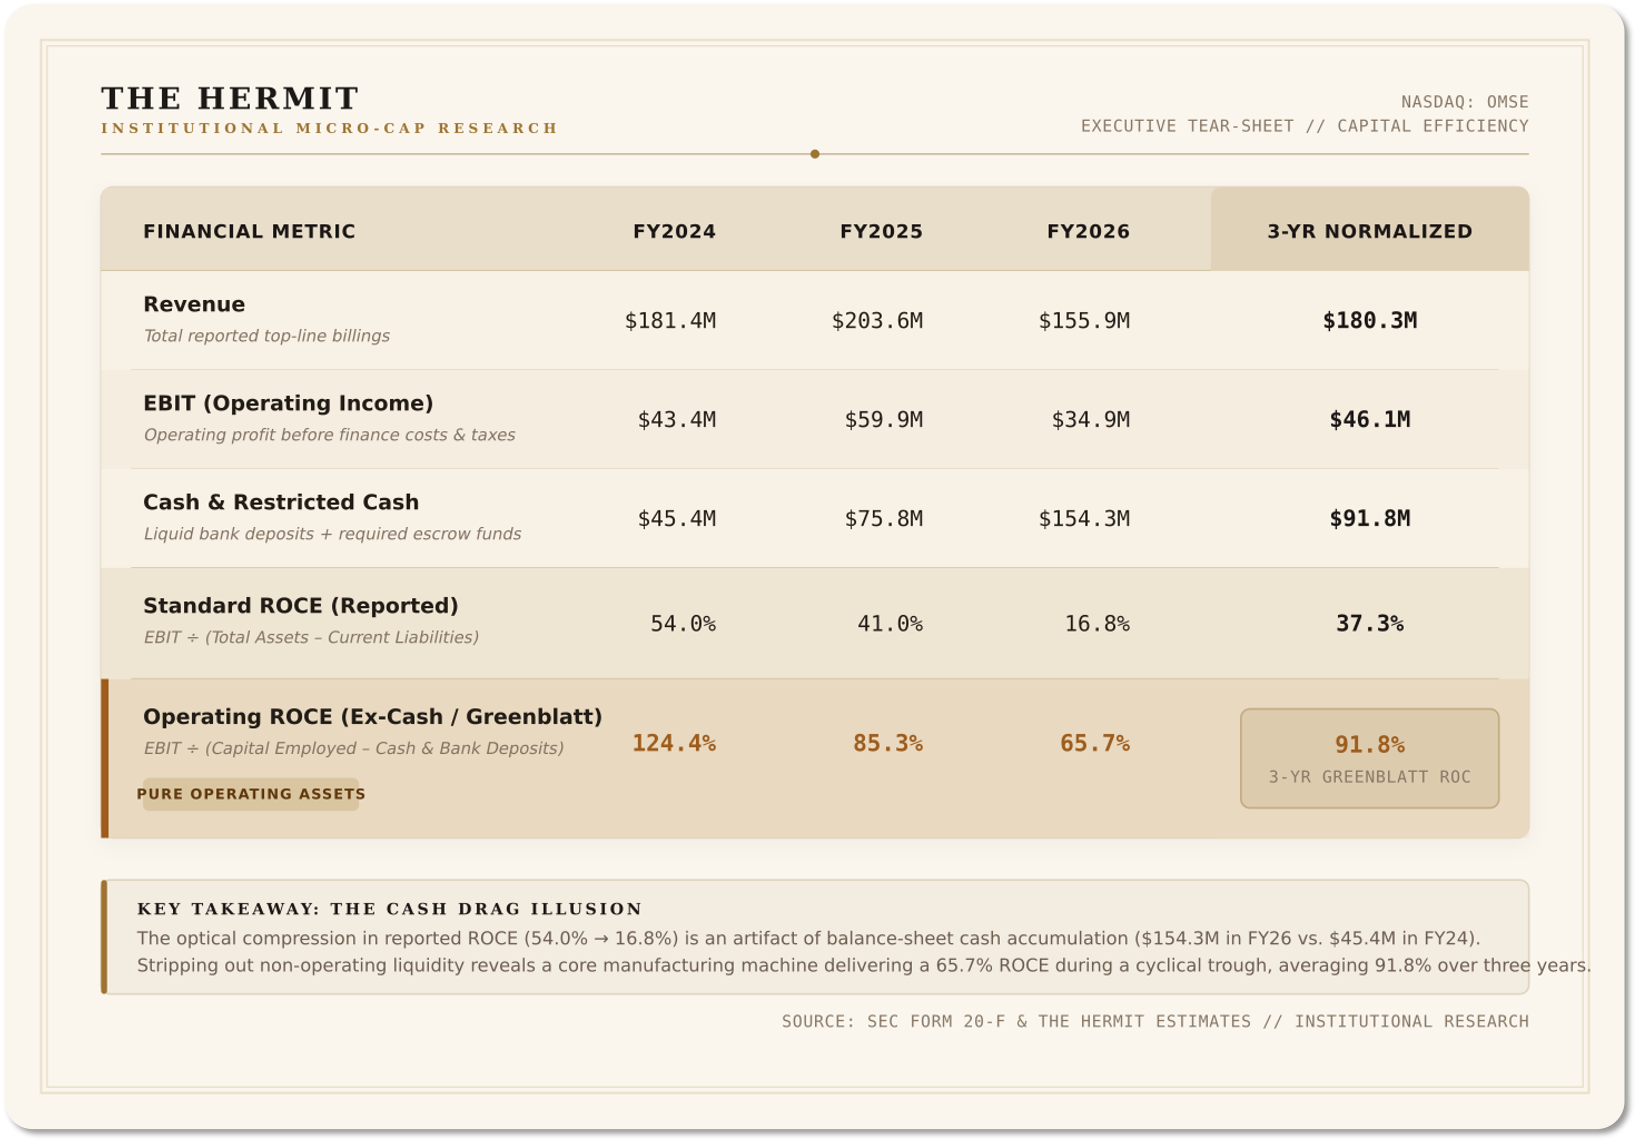
In case you’re still unsure, here are the ROCE stats for option D:
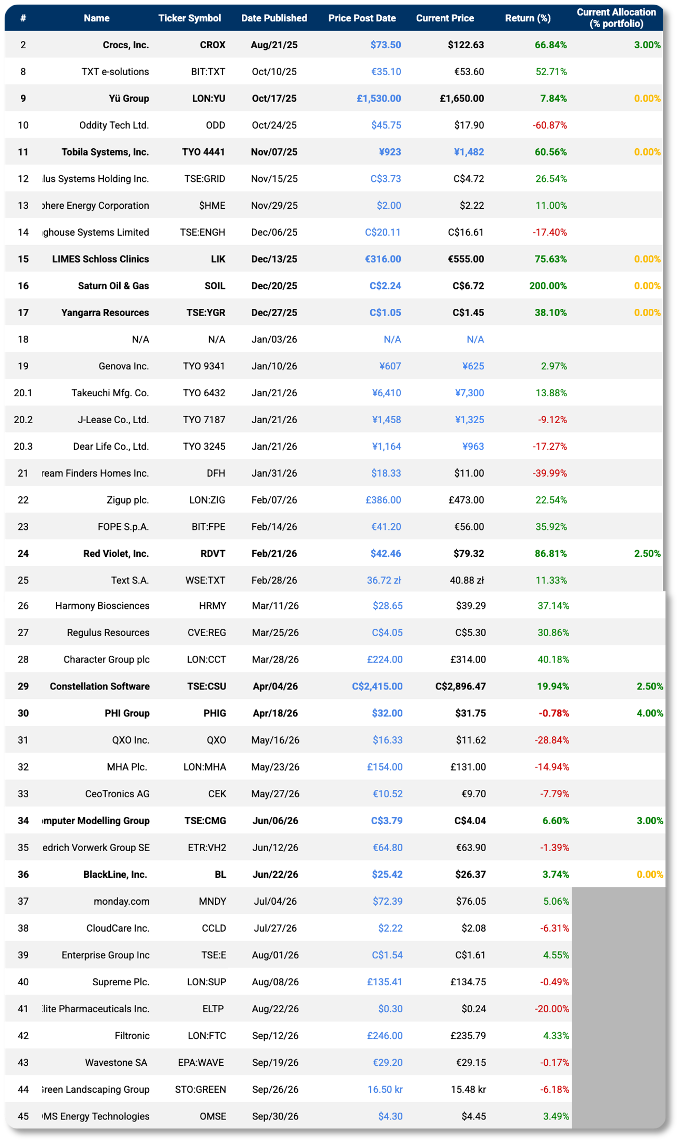
As we now do every week for transparency, here is our list of past Pick of the Week posts and their returns since publishing:
All picks (equally weighted): +15.93%

Pick of the Week. A curated series of high-conviction research on companies currently under our microscope. We screen for specific dislocations where the market has mispriced the balance sheet or earnings power (or both).
None of the following should be construed as investment advice. Please consult a financial advisor before making any investment decision. You will find a full disclaimer at the end of this post.

🛢️ OMS Energy Technologies Inc. ($OMSE)
⭐ Overall Grade: 8.0 / 10
We originally discovered OMSE while deep in the weeds researching CMG.
While both sit squarely in oilfield optimization, OMS carved out a wildly profitable niche on the physical hardware side, effectively anchored in the Middle East and Southeast Asia with an iron grip on shallow offshore and platform operations.
We actually just spoke directly with OMSE’s senior management a few days ago.
If you know our playbook, that executive check is always the capstone of our primary scuttlebutt process. Let’s call it a final sanity check.
While we won’t share direct quotes, you bet we’ll include verified insights from that discussion.
OMS Energy Technologies (NASDAQ: OMSE) is an upstream oilfield hardware and precision-engineering specialist that manufactures the high-spec metal components holding oil and gas wells together at the surface and just below the seabed.
It operates in an unpopular spot, as what’s in vogue are the much deeper offshore facilities.
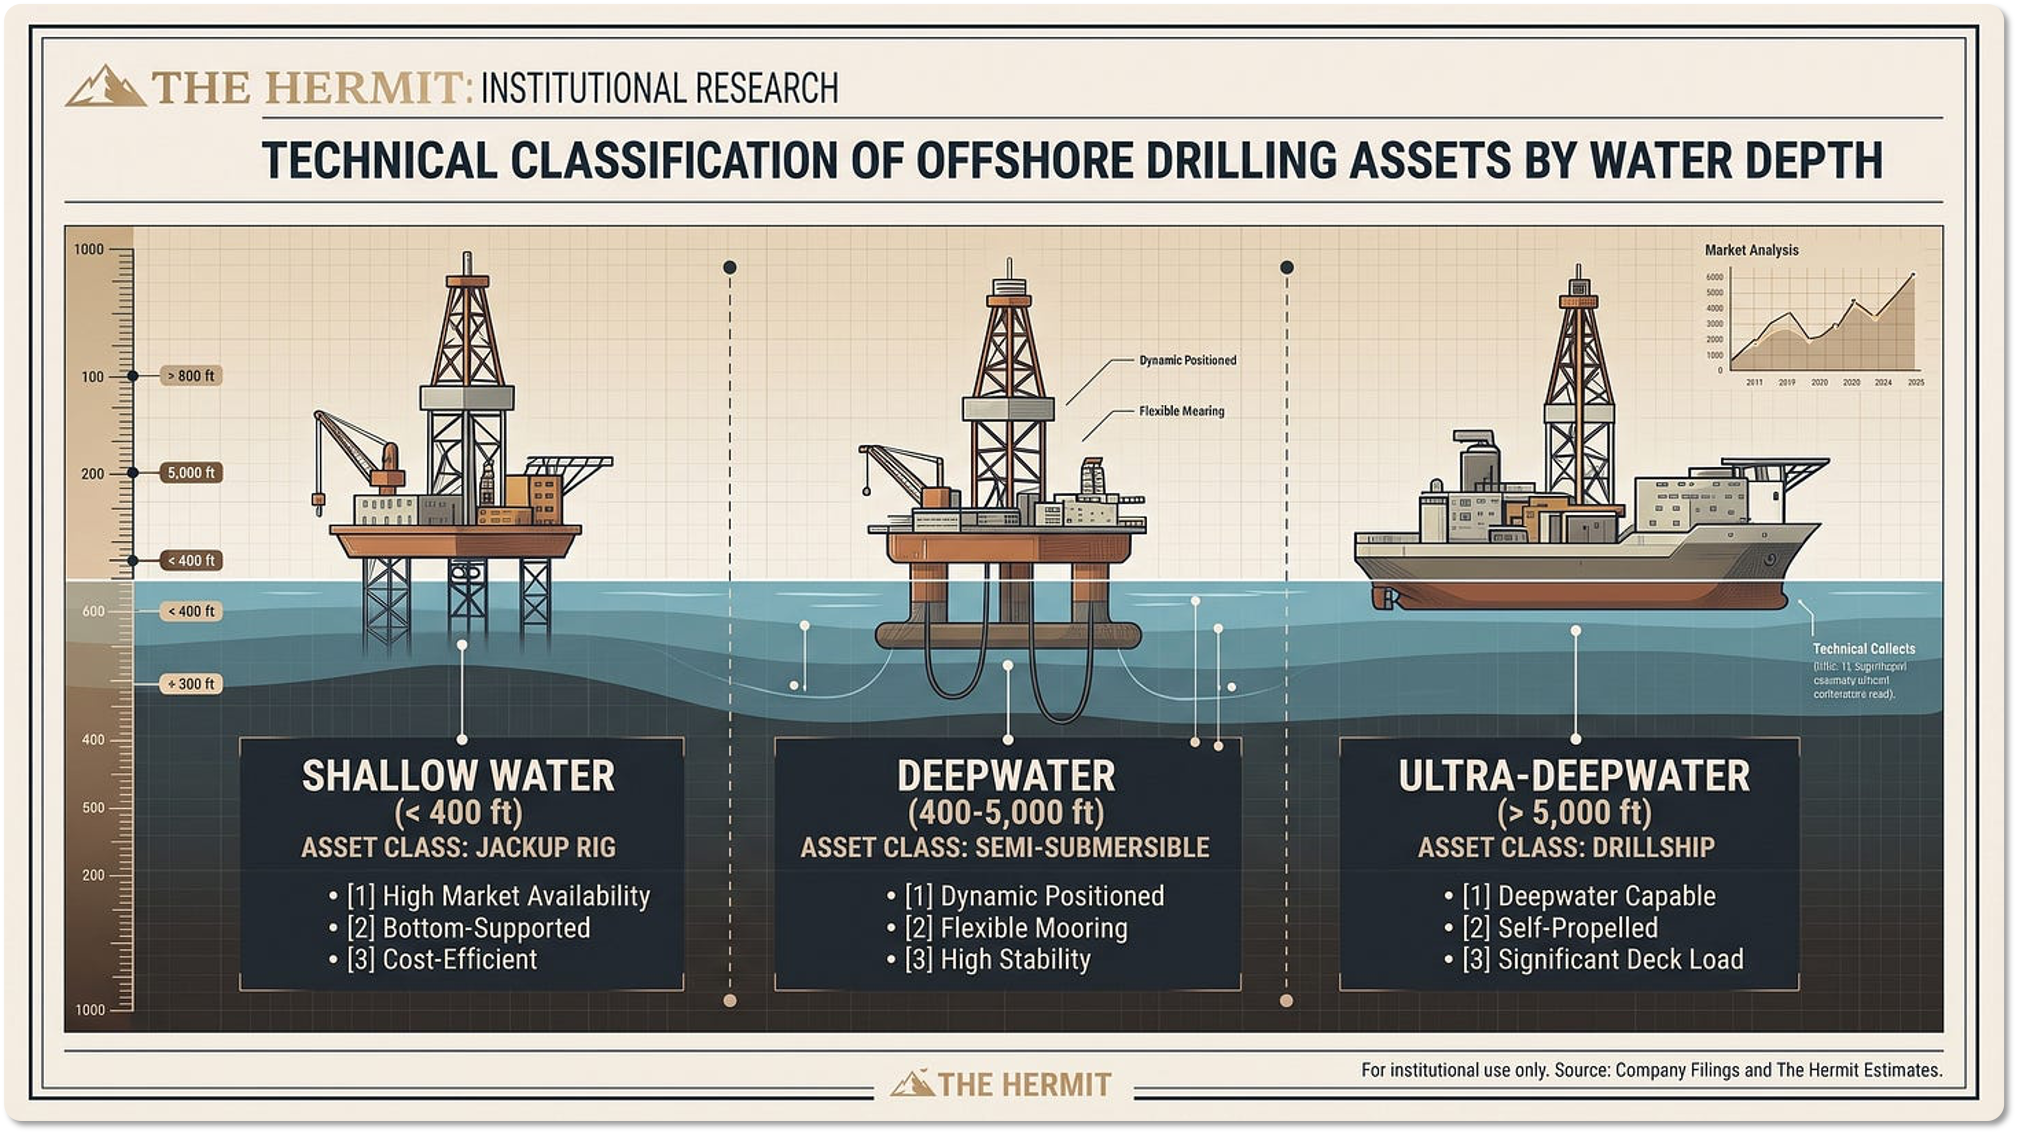
Shallow-water offshore drilling has fallen out of favor primarily because it centers on mature brownfields with declining production profiles.
The multi-billion-dollar capex cycles and massive reserve discoveries that capture excitement are flowing almost exclusively toward frontier deepwater and ultra-deepwater plays like Guyana, Brazil, and West Africa, leaving the more traditional shallow-water platforms out of the spotlight.
Compounding this lack of excitement is severe dayrate and contract volatility across the jackup space.
Supply additions over recent years were met with abrupt regional pauses. The most explicit example is when Saudi Aramco suspended dozens of jackup rigs to recalibrate its maximum sustainable capacity targets. This all casts a cynical shadow across the entire shallow supply chain.
Lastly, shallow operations basically carry a commoditization stigma. A very large group of people are writing off standard surface wellheads and conductor casing as basic, interchangeable metal, contrasting it unfavorably against their 50-million-dollar subsea blowout preventers and wet trees engineered by global giants that we’ve looked at before like SLB, Baker Hughes, or TechnipFMC.
If we had to summarize all of this into a single sentence, it would be: software over hardware.
How Does OMS Make Money?
OMS operates across six core jurisdictions: Saudi Arabia, Singapore, Indonesia, Thailand, Malaysia, and Brunei. They operate 11 precision manufacturing and service facilities. The company generates revenue across four distinct revenue streams:
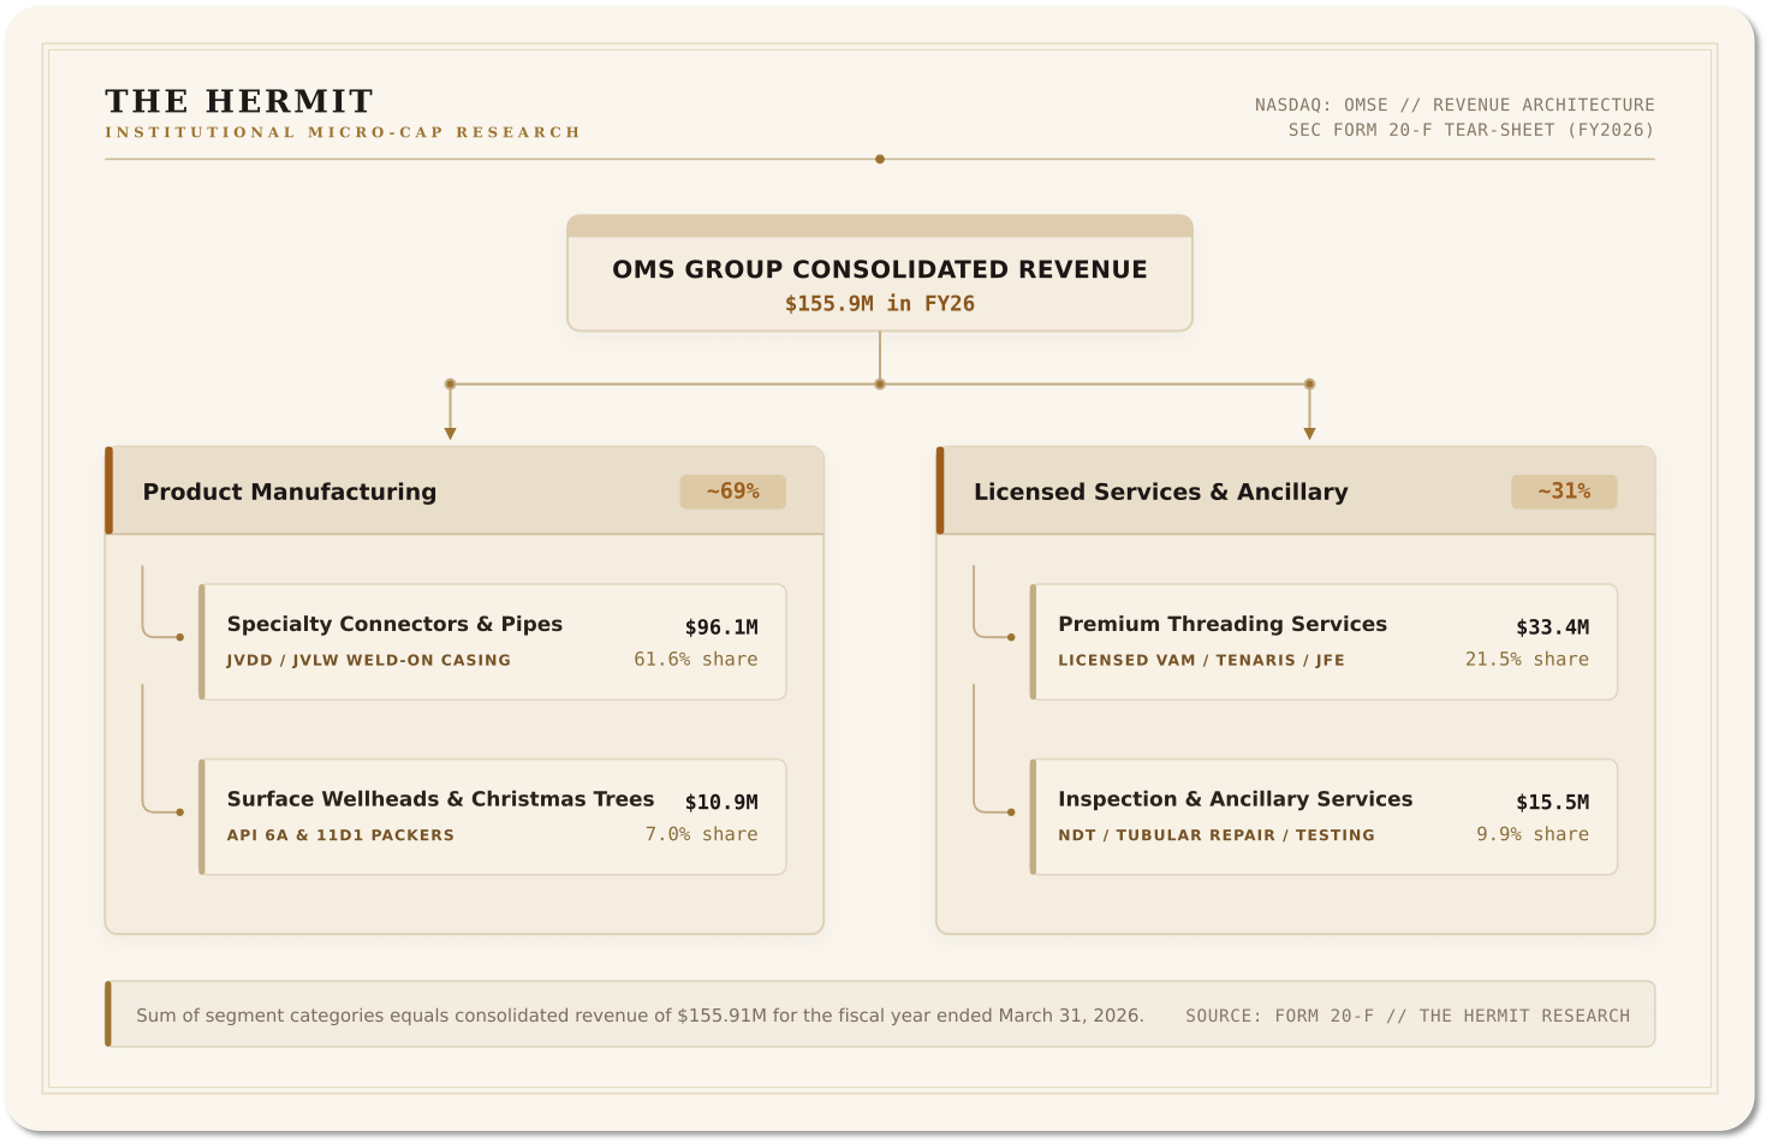
Let’s break these down:
Specialty Connectors and Pipes (61.6% of FY26 Revenue)
These are large-diameter (16 inches and up) welded joints and conductor casings. These heavy steel pipes are driven or drilled into the ground/seabed to form the foundational structural column of a well.
OMS’s proprietary connections (the JVLW and JVDD series) feature fast make-up thread designs (often 1 to 3 rotations to lock) that save rig crews hours of offshore rig time, where daily spread rates can exceed hundreds of thousands of dollars.
The massive Dammam facility in Saudi Arabia accounts for 95% to 99% of this segment’s sales, delivered directly to Saudi Aramco under a 10-year Long-Term Agreement (LTA) running through 2033.
Surface Wellhead Systems (SWS) & Christmas Trees (7.0% of FY26 Revenue)
This is the complex stack of mechanical valves, casing heads, and chokes sitting directly on top of the well to control pressure (up to 10,000–15,000 PSI) and fluid flows.
Centered in Indonesia (87% of segment revenue), primarily serving Pertamina Hulu Rokan. OMS also holds API Spec 11D1 certification to manufacture its own mechanical and hydraulic downhole retrievable packers, recently expanding into Pakistan, Oman, and Angola.
Premium Threading & Ancillary Services (31.4% of FY26 Revenue)
This part of the company centers around high-precision threading of Oil Country Tubular Goods (casing and tubing) under proprietary licenses from global pipe giants (VAM, Tenaris, JFE, Hunting, NOV Grant Prideco).
It’s effectively a pure toll-booth. Recurring service revenue. Exploration operators purchase seamless pipe, and OMS cuts patented, leak-proof micro-groove threads into the pipe ends before it goes downhole.
To understand whether OMS’s product is good, you have to look at how oil and gas equipment is judged in the field.
In upstream oil and gas, “quality” is very well defined by two unforgiving criteria:
(1) failure rates under extreme physical load and
(2) qualification credentials required by National Oil Companies (NOCs).
If an iPhone has a bug, the app crashes. If an offshore conductor casing joint or a 10,000-PSI surface wellhead shears or leaks downhole, the operator faces an environmental blowout, millions (USD) in rig downtime, and a big bag of liabilities.
Because of all of these, operators never buy unproven equipment on price alone.
OMS’s product suite is technically proven, highly certified, and trusted at the highest tier of the industry.
Prop. Connectors: The JV Series
OMS’s core proprietary hardware line is the JV Family of weld-on casing connectors (JVDD, JVDD2, and JVLW).
These are large-diameter mechanical joints (16” to 36” nominal pipe) used to lock together the top foundation pipe that anchors an offshore or onshore well.
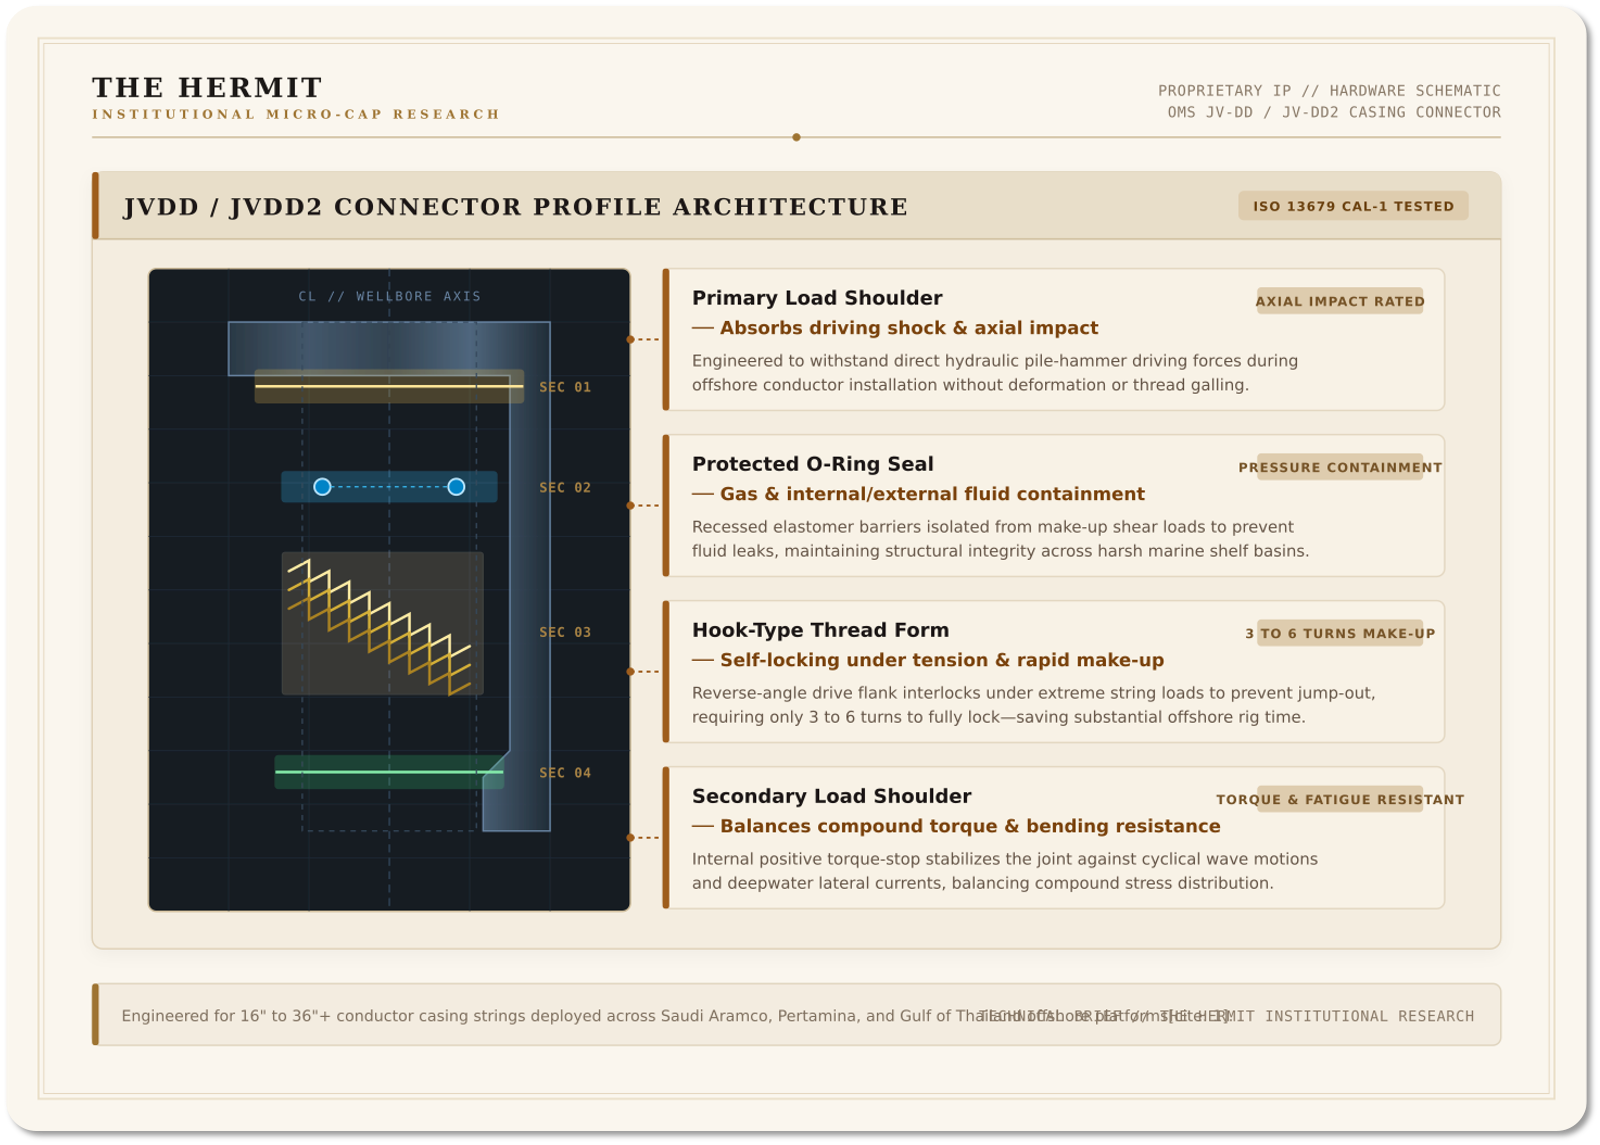
Standard pipe requires long make-up times and carries a high risk of cross-threading. The JVDD series uses a low-ramp angle, multi-start thread design requiring as few as 3 to 6 turns to achieve full make-up torque. On a deepwater drillship costing $300,000+ per day, shaving hours off casing runs saves the client tens of thousands of dollars per well.
Unlike standard threaded pipes that warp or crack if hammered into dense seabed rock, OMS connectors feature dual load shoulders designed to withstand repetitive, high-impact hydraulic driving apparatus strikes without deformative yield.
The JV connection line underwent finite element analysis (FEA) and destructive physical validation by independent engineering consultants in Singapore and Houston, formally passing ISO 13679:2002 CAL-1 (Connection Assessment Level 1) physical test standards.
Surface Wellheads, Christmas Trees & Downhole Packers
OMS manufactures complete onshore and offshore surface wellheads rated up to 10,000 to 15,000 PSI working pressures, as well as production Christmas tree valve blocks.
API Specification 6A Monogram: API 6A is the gold standard for surface well control equipment. OMS holds this license across multiple plants, including securing API 6A certification for its primary Dammam facility in Saudi Arabia in early 2026. This allows OMS to supply and service complete Christmas trees directly to Saudi Aramco.
Downhole Tools (API Spec 11D1): In late 2025, OMS Indonesia developed and earned API 11D1 certification for its proprietary retrievable mechanical and hydraulic downhole packers. Packers must reliably isolate casing rings under high-differential pressures downhole—a technical step up from standard surface piping.
Field Acceptance: Pertamina Hulu Rokan (Indonesia’s largest oil producer) repeatedly extended OMS’s contracts in FY26 beyond baseline award values because of product reliability in steam-flood and conventional basins. In FY26, OMS secured its first 10,000-PSI full wellhead system deployment in Pakistan, as well as customer wins in Angola and Oman.
Premium Threading (Licensing)
Perhaps the clearest validation of OMS’s precision quality is that the world’s most protective seamless pipe manufacturers (VAM (Vallourec), Tenaris, Hunting, NOV Grant Prideco, and JFE) license OMS to machine their patented thread profiles.
These pipe manufacturers spend hundreds of millions developing proprietary gas-tight metal-to-metal seal threads.
They only license machine shops that can repeatedly achieve microscopic CNC tolerances (within thousandths of an inch) under strict API Spec Q1 quality management systems.
If OMS had loose QA/QC or high scrap rates, those licensors would revoke their machine shop agreements immediately to preserve their brand integrity. OMS has held these licenses across Southeast Asia and the Middle East for decades.
Product Scorecard (vs. peers)
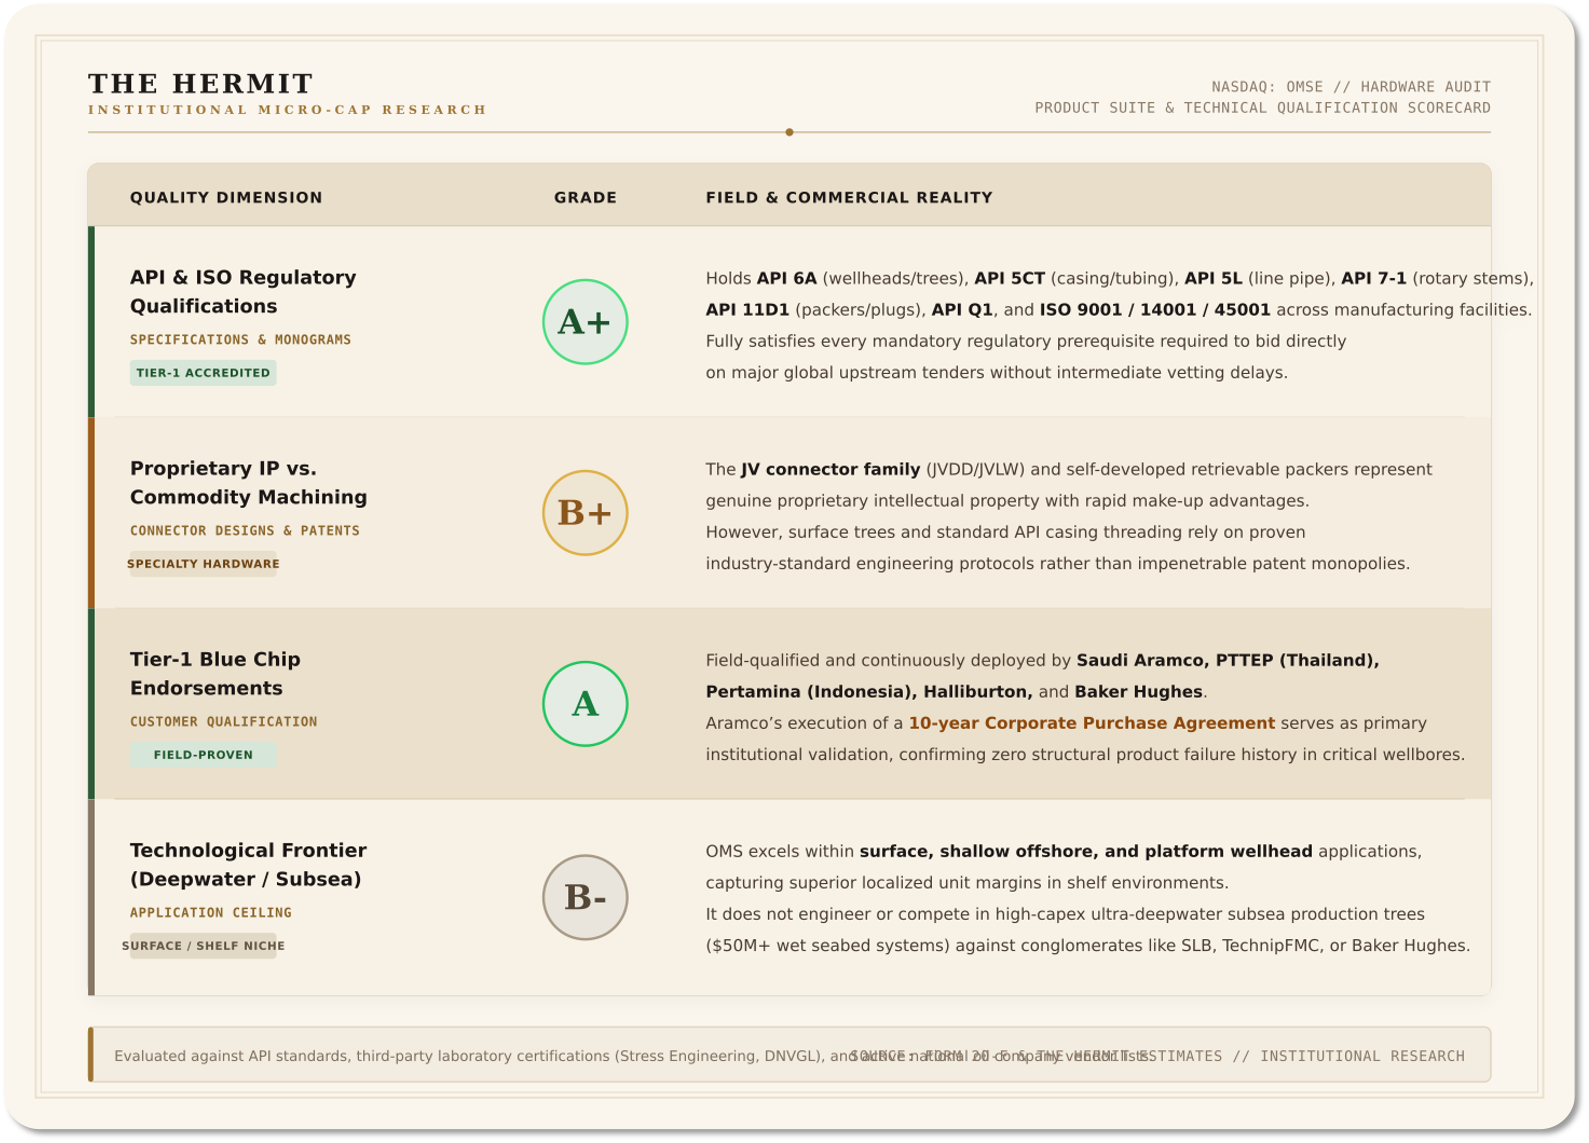
OMS’s product is not bleeding-edge, but it does operate in a safety-first, low-risk tolerance environment where proven reliability is everything.
In its target market (onshore, shelf, and shallow-water upstream wells across the Middle East and Asia-Pacific), OMS’s hardware is thoroughly proven, fully certified, and trusted by the most demanding national oil companies in the world.
Contract Structure: Are Revenues Truly Recurring?
In software or consumer staples, recurring revenue means predictable, contractually locked subscriptions. In the upstream oilfield sector, revenue is rarely contracted as a fixed monthly retainer.
OMS uses an Installed-Capacity Framework Agreement model.
While long-term master contracts are multi-year and provide continuous customer exclusivity, actual revenue realization is lumpy and volume-dependent.
Revenue recurrency is driven by “Call-off Orders” (purchase orders issued on demand under fixed pricing agreements) rather than guaranteed minimum take-or-pay volume commitments.
Contract Count & Core Agreement Inventory
OMS has served over 200 upstream clients, but consolidated business visibility rests on a core set of long-term master agreements and framework supply contracts:
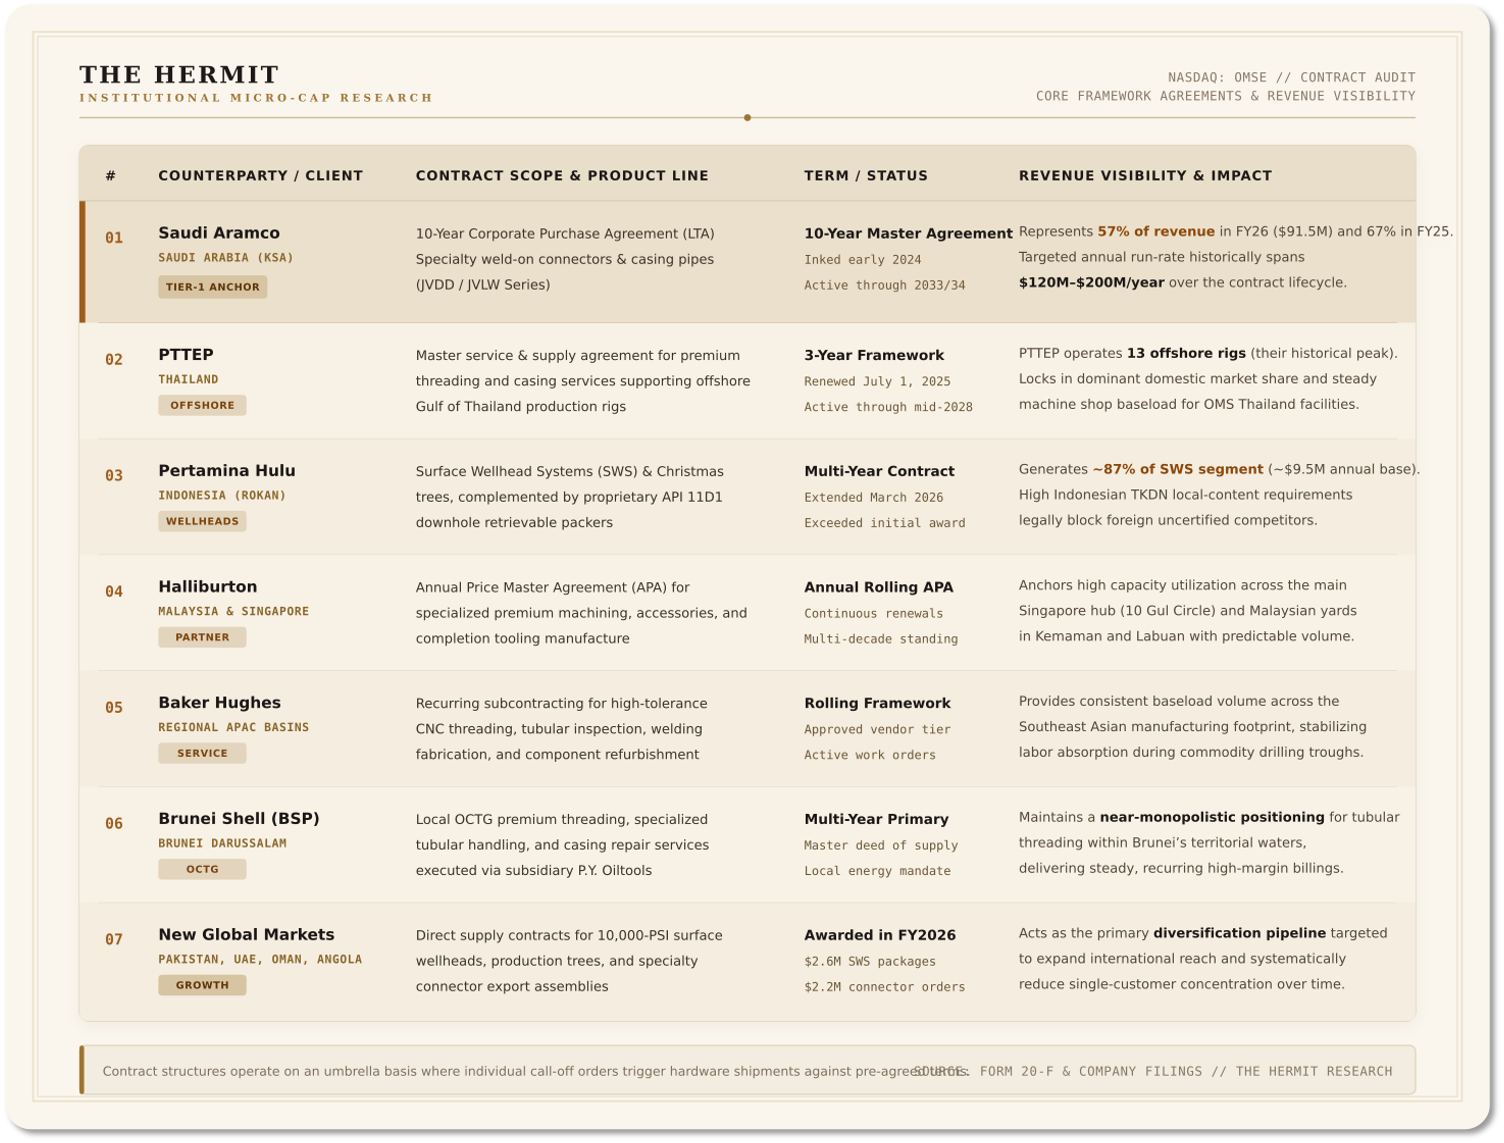
The Nature of Recurrence: Revenue vs. Cash Flow
The Call-Off Order “Whiplash”
A long-term contract at OMS is not an annuity. Saudi Aramco’s 10-year LTA is an umbrella agreement that fixes unit prices and technical qualifications, but Aramco orders in batches via call-off purchases:
FY2025: Revenue spiked to $203.6m because Aramco was winding down an older contract while overlapping the aggressive ramp-up of the new 10-year LTA.
FY2026: Revenue fell 23.4% to $155.9m when call-offs normalized and Aramco temporarily digested inventory.
This dynamic explains why backward-looking stock screens mistakenly flag the company as declining, even though the master 10-year relationship remains intact.
The 12-Month Visible Order Backlog
OMS tracks short-term guaranteed visibility using its firm order backlog (orders scheduled for delivery within the next 12 months):
March 31, 2025 Backlog: $102.0m
March 31, 2026 Backlog: $60.7m
Management explicitly notes that backlog contraction was not due to lost tenders or cancellations, but purely the timing interval between major Aramco call-off tranches.
For instance, right at fiscal year-end in March 2026, OMS booked a fresh $11.0m call-off order from Aramco to kick off FY27.
Premium Threading: “Consumable” Baseload
While connector projects come in multi-million dollar batches, the Premium Threading and Ancillary Services divisions ($48.9m combined revenue in FY26) act as steady, recurring consumables. Every time an operator runs casing into a new development well, pipe joints require threading and NDT inspections. Operators do not alter their casing thread suppliers mid-drilling program due to downhole blowout liabilities.
Quality of Earnings Assessment (Quick Summary)
Contract Duration:
High(Anchored by a 10-year agreement with the world’s largest oil producer through 2033 and a multi-year partnership with Thailand’s PTTEP through 2028).Revenue Volatility:
ModeratetoHigh(Zero minimum volume guarantees mean revenue swings year-to-year based on NOC budgeting cycles).Customer Retention:
Exceptional(NOC relationships span 20 to 50 years, with virtually zero historical contract cancellations).
The revenue is pretty sticky over a 3- to 10-year horizon, but lumpy on a quarterly and annual basis.
For an investor, this lumpiness creates mispricings which are basically entry opportunities for us.
Note that the underlying multi-year master supply agreements remain there, which means visibility.
The Unit Economics: Dissecting the Cost Stack
OMS is not a basic foundry; it operates an integrated precision machining and fabrication model. It buys certified heavy steel casing, pipes, and forged bar stock from regional mills, machines high-tolerance threads, welds specialty connectors onto conductor pipe sections, and performs non-destructive testing (NDT).
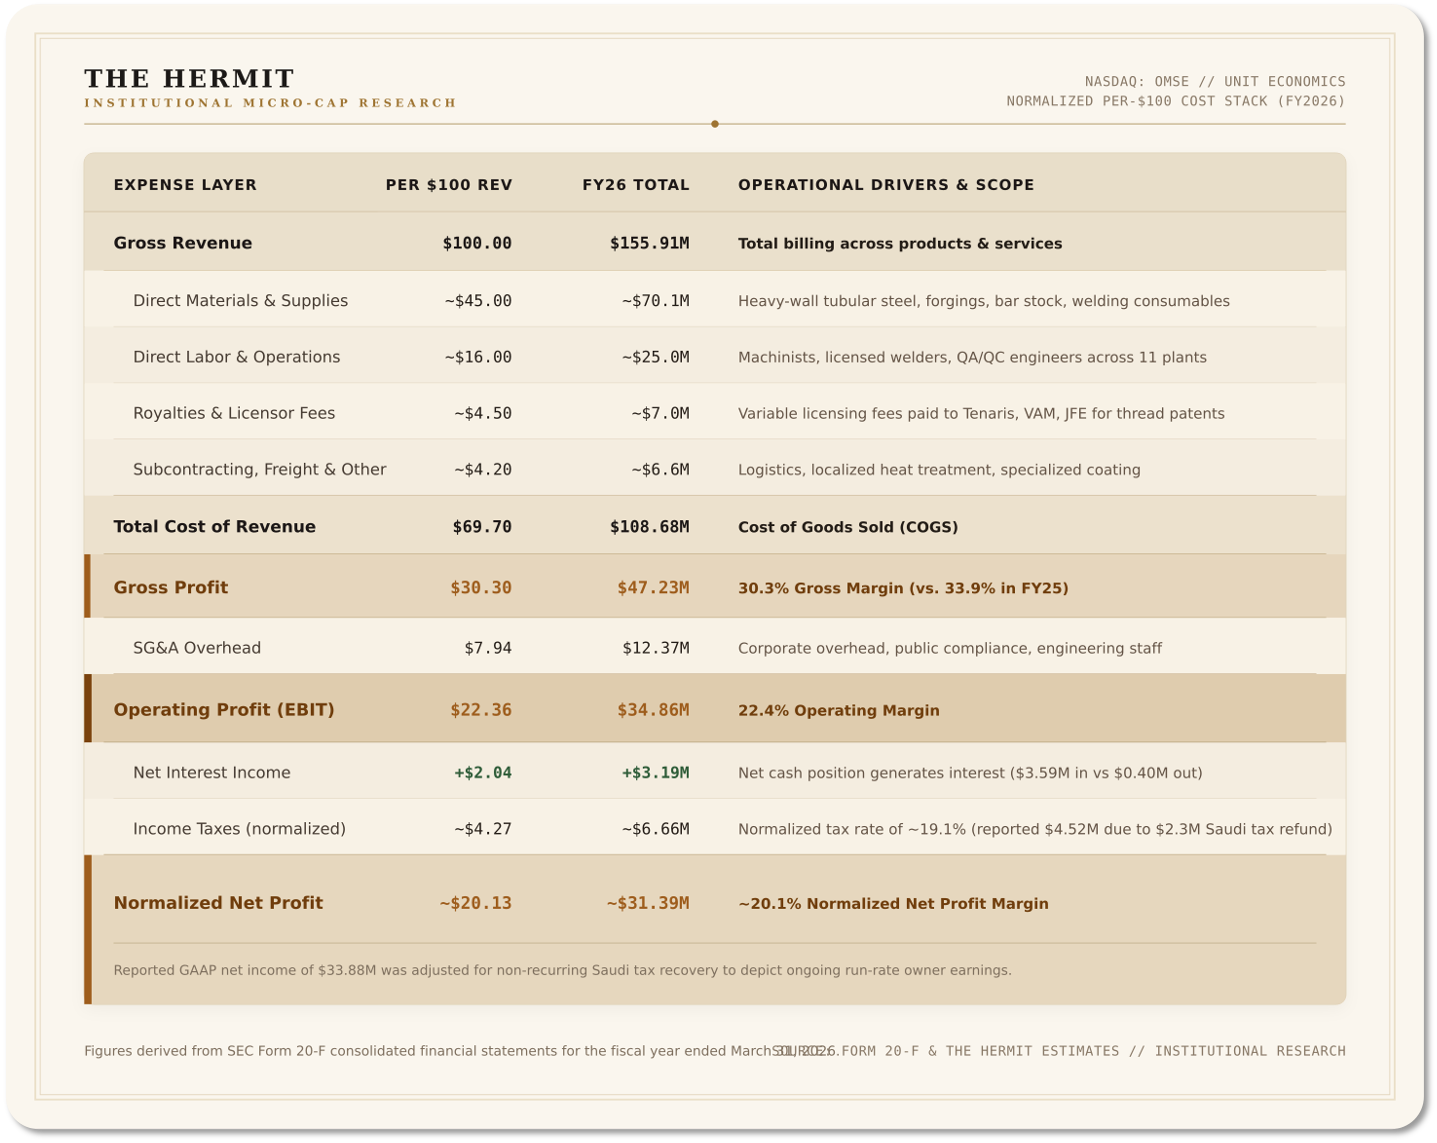
Segment Gross Margin Profile
Specialty Connectors & Pipes: Delivers ~29.6% gross margin ($28.5m gross profit on $96.1m revenue in FY26). Highly sensitive to raw steel input prices and volume absorption in Saudi Arabia.
Surface Wellheads & Trees: Delivers ~28.3% gross margin ($3.08m gross profit on $10.9m revenue). Compressed slightly by higher imported raw material components.
Premium Threading Services: Historically the highest-margin segment, delivering 28.3% to 40%+ gross margin. Threading carries little raw steel inventory risk; costs are predominantly machinist hours, machine wear, and variable patent royalty cuts.
Ancillary Services: Delivers ~40.1% gross margin ($6.2m gross profit on $15.5m revenue in FY26), reflecting pure testing, refurbishing, and inspection labor.
Working Capital Dynamics and Cash Conversion
The unit economics of this business are shaped by its cash conversion cycle:
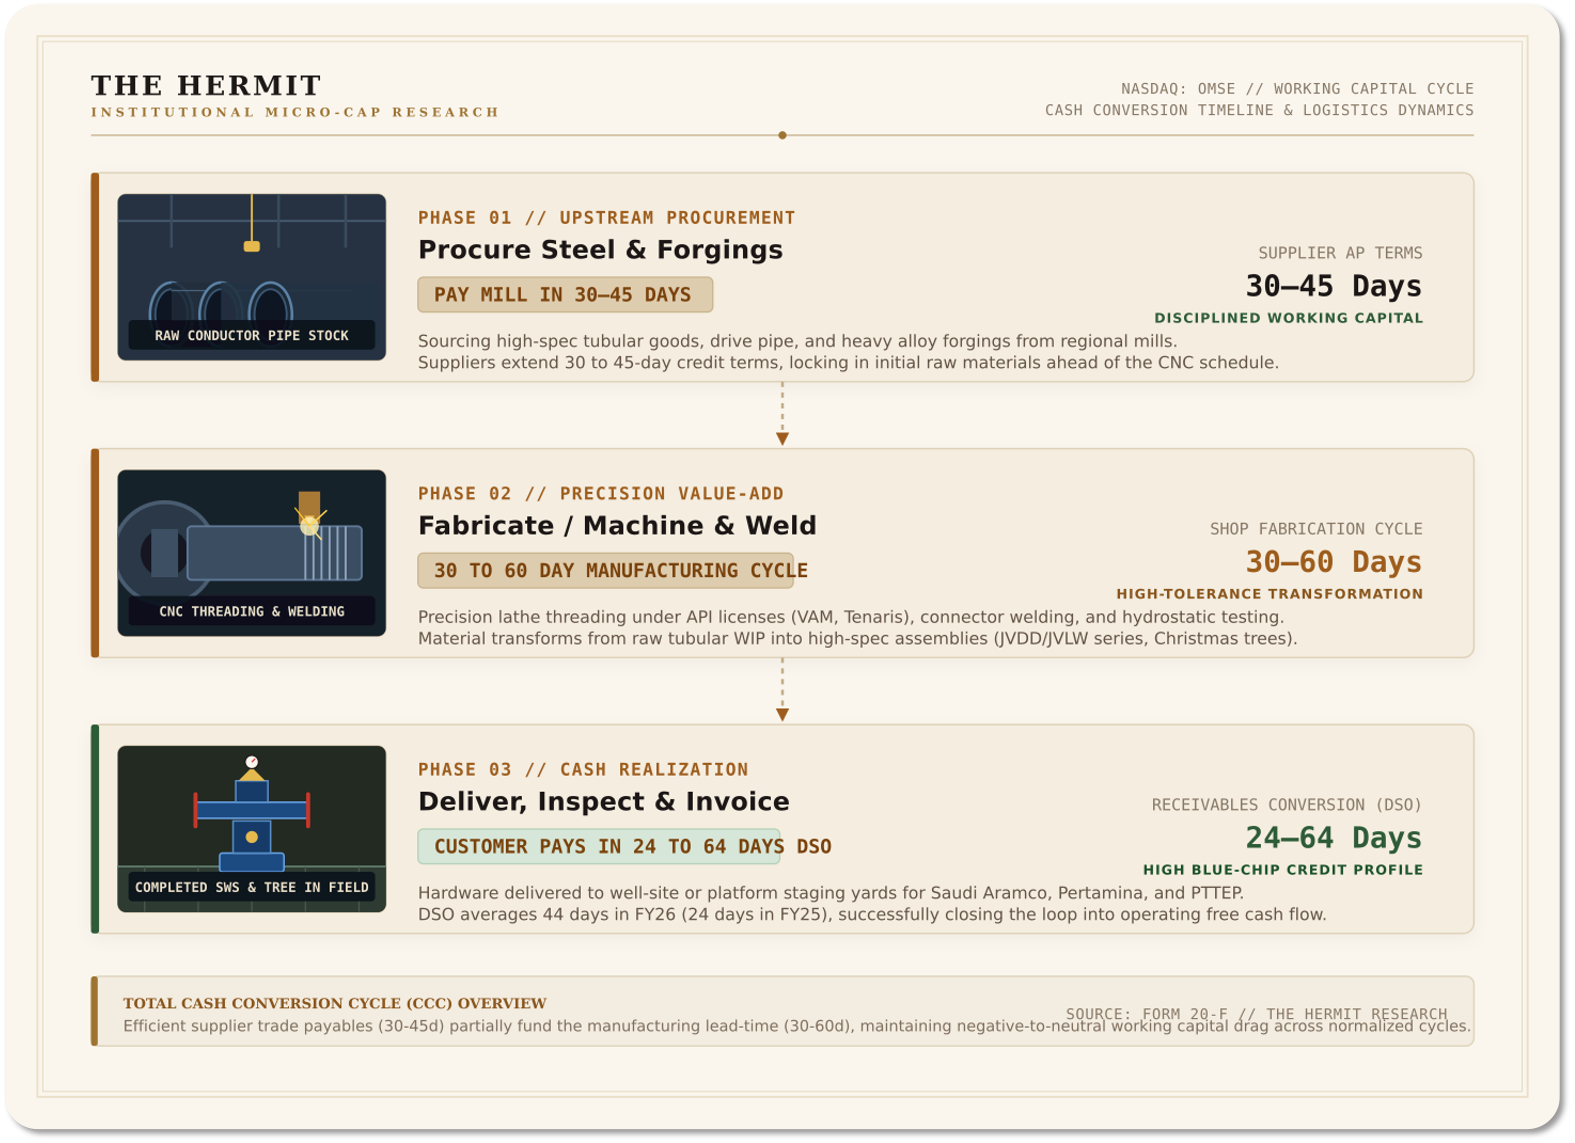
Receivables & Payables: In FY26, Days Sales Outstanding (DSO) sat at 44 days, while suppliers were paid in ~46 days.
Inventory Run-Down as a Cash Spigot: In FY25, OMS stocked up heavily ($32.5m inventory) ahead of expected Saudi Aramco call-off orders. In FY26, as Aramco orders normalized, OMS converted that raw inventory down to $17.2m, which released $16.2m in working capital straight into cash.
Capex Lightness: Manufacturing these tools does not require massive smelters or shipyards. OMS incurred just $1.64m in total Capex in FY26 ($1.11m PPE + $0.52m intangibles) against $155.9m in revenue (a Capex intensity of barely 1.05% of sales).
Cash Conversion: Because maintenance Capex is negligible, OMS generated $54.1m in operating cash flow and $52.5m in Adjusted Free Cash Flow in FY26.
How can Baseline make your life easier?
As you know, we’ve partnered with Baseline to get you an easy way to verify whether a company is worth your time.
Baseline helps you screen for and analyze companies, identifying potential issues from the very first pass.
It aggregates information on where the company is going and what the key risks are in terms of business quality, competitive advantages, and AI.
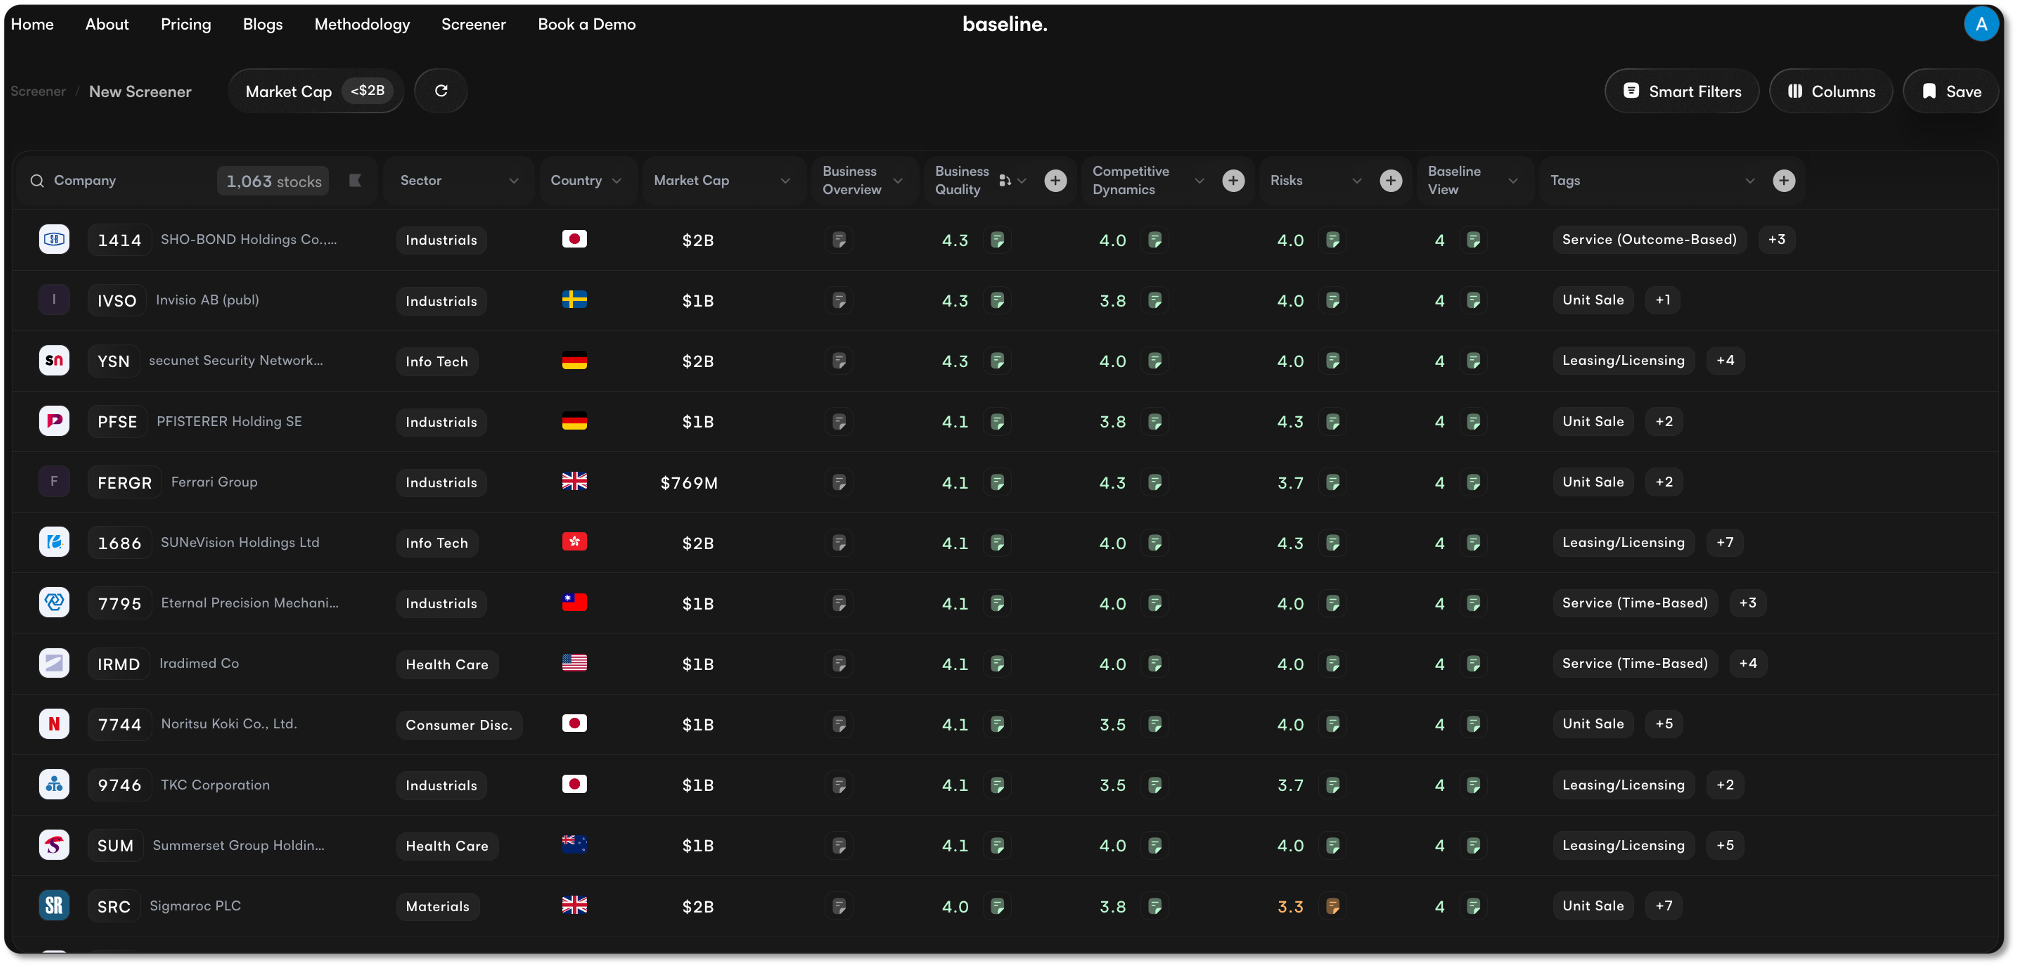
Of course, none of this replaces a much deeper analysis that you must conduct before deciding with adequate conviction, and we think the best way of doing that is by performing a full scuttlebutt rundown.
Baseline, however, accelerates the process of discarding companies, which saves you time and allows you to focus more on what’s important.
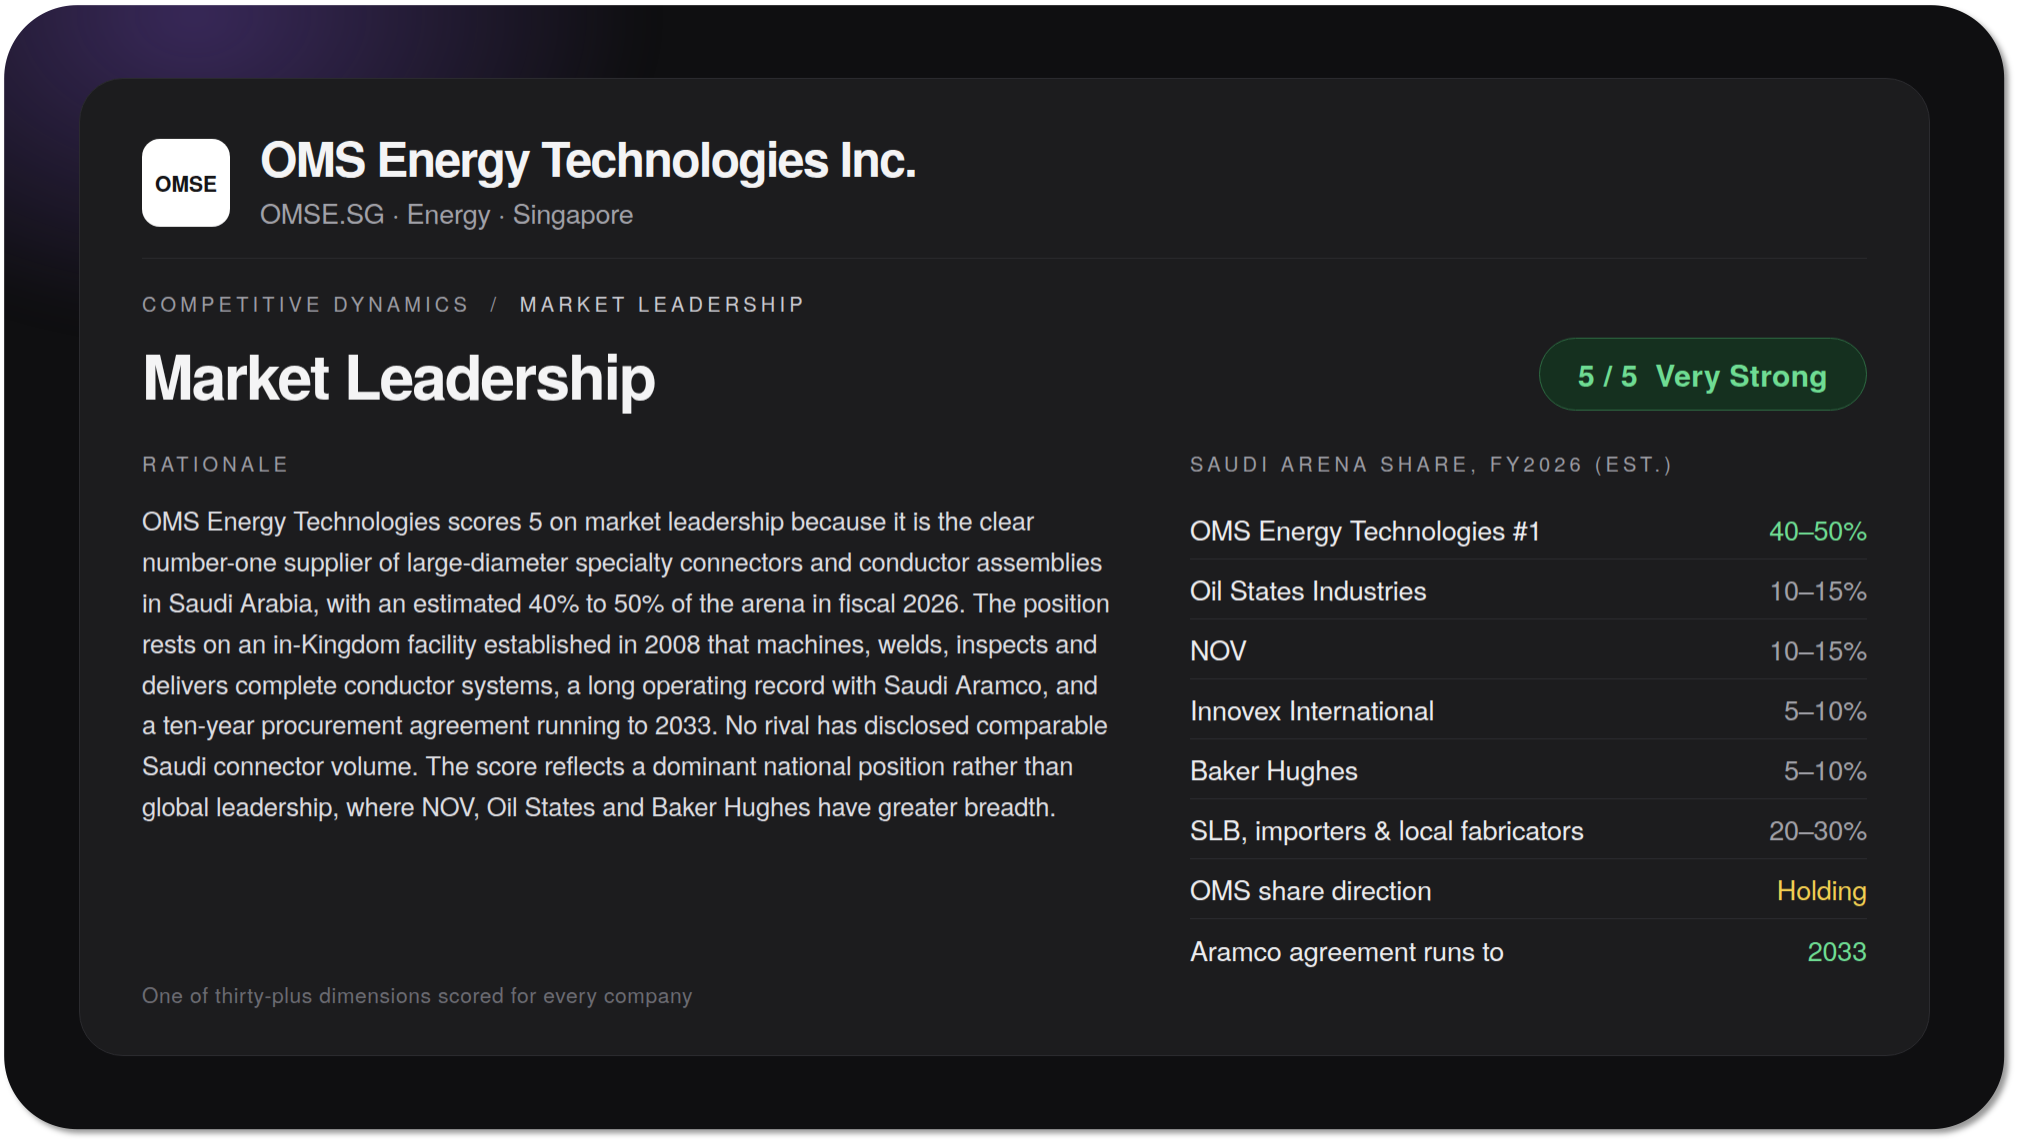
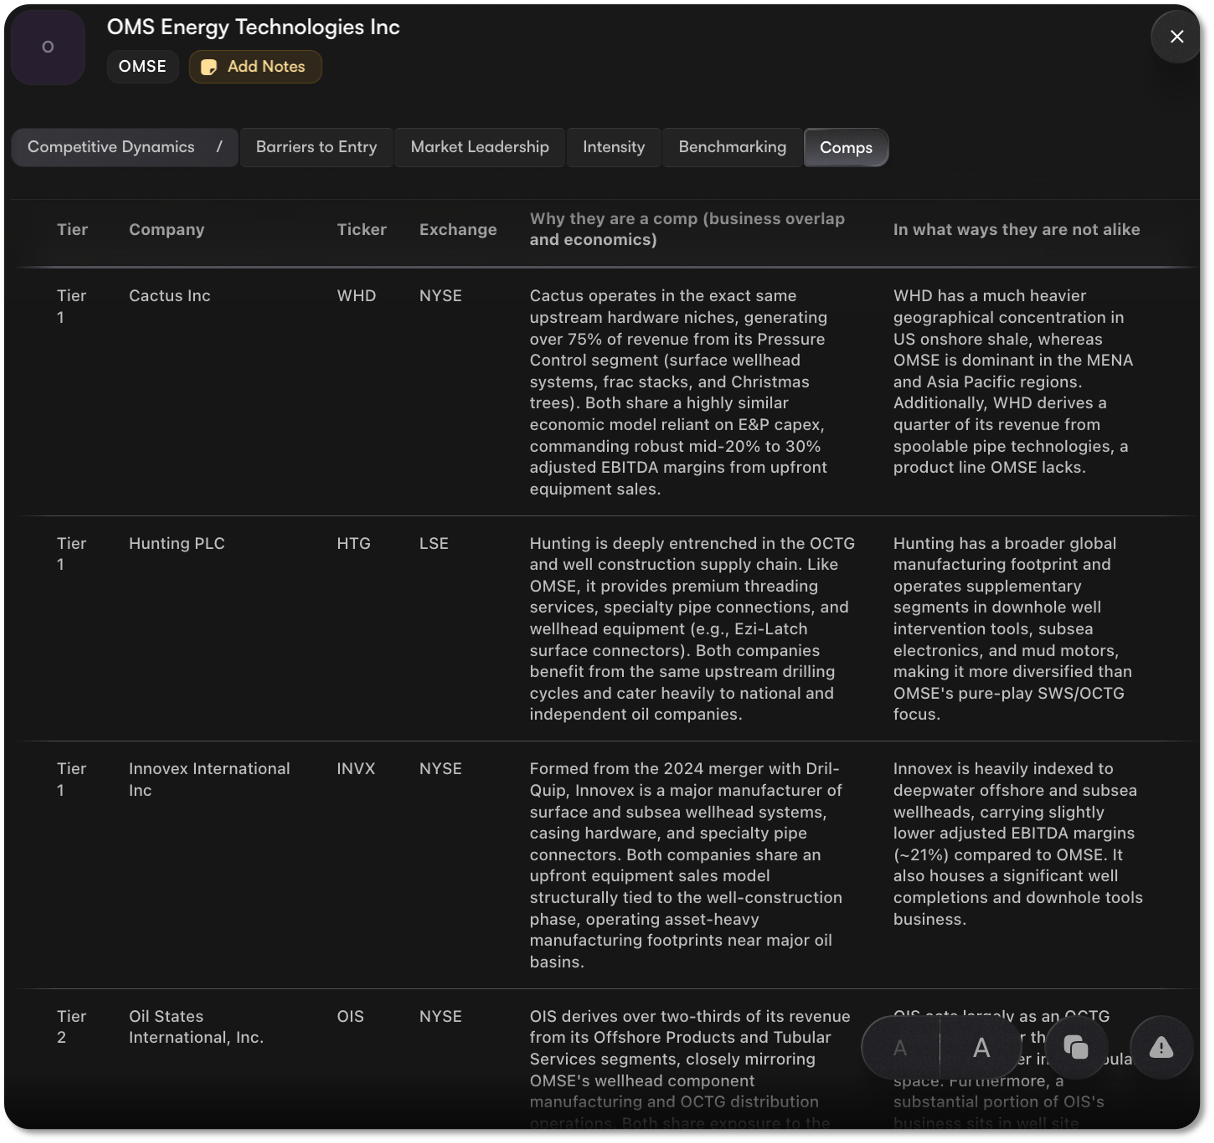
You don’t have to take our word for it; here’s the report for a few companies we love and hold so you can see firsthand what we’re talking about:

🎯 Catalysts: Why Now?
Initiating Cash Returns
The company holds $154.3m in cash and restricted cash (against an ~$185m market cap) with zero bank debt.
Because this cash sits largely in short-term bank deposits earning modest yields, it dilutes headline ROE and fuels market skepticism that the cash is “trapped” or earmarked for empire-building.
For us shareholders, the solution is super straightforward:
Initiating a regular dividend, a one-time special dividend, or an accretive share repurchase program.
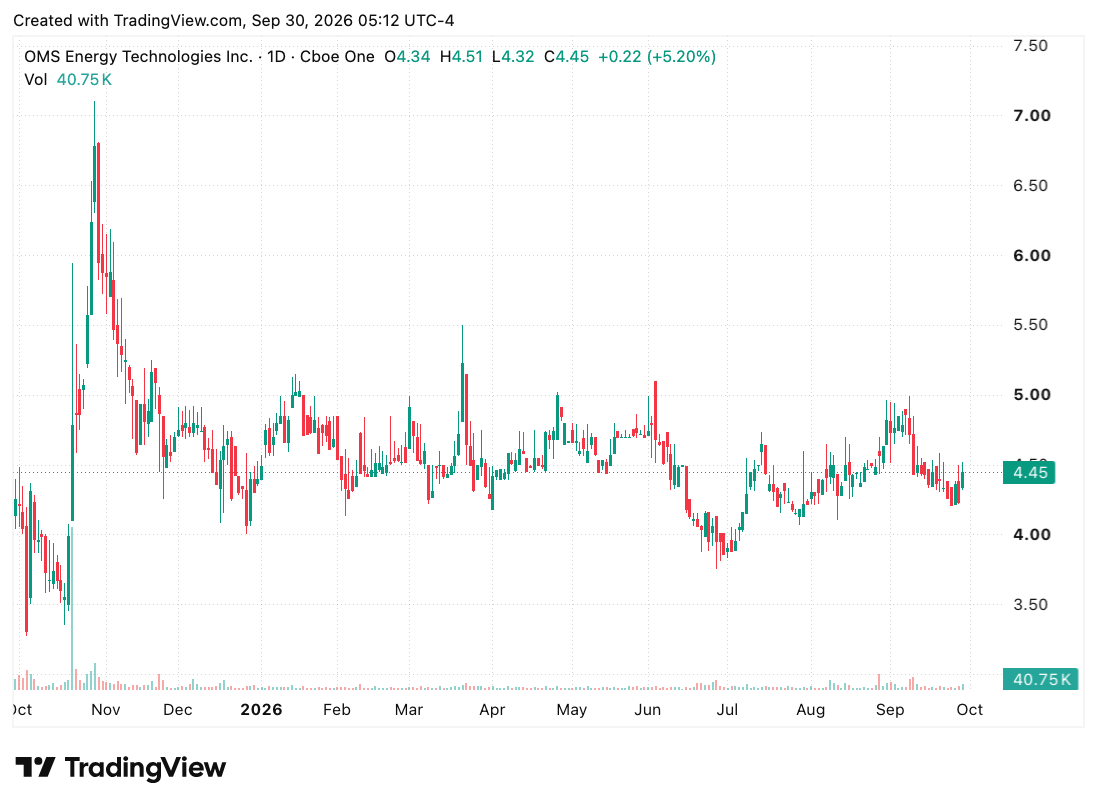
With the stock trading around book value ($4.03) and cash backing ~$3.60 per share, buybacks at current levels would be heavily accretive to per-share intrinsic value.
Even establishing a modest 4%-6% dividend yield would cost less than $10m annually, a fraction of FY26’s $52.5m in Adjusted FCF, instantly putting the stock onto institutional income screens.
Saudi Aramco Call-Off Resumption & Revenue Normalization
This is also an easy one. Revenue fell from $203.6m in FY25 to $155.9m in FY26 as Aramco call-off orders normalized following an overlap period between supply contracts. Algorithmic screens and quant models see this as a red flag (top-line decline) rather than normal contract timing.
Sequential reacceleration of call-off purchase orders under the active 10-year Corporate Purchase Agreement (LTA) through 2033 would change everyone’s perception.
The $11m call-off order booked right at the end of FY26 in March was the first sign of this replenishment.
Once upcoming quarterly filings demonstrate that the Aramco baseline has stabilized back toward its historical $120m–$200m multi-year run-rate, the market’s “terminal decline” narrative should break.
Diversification Beyond Aramco
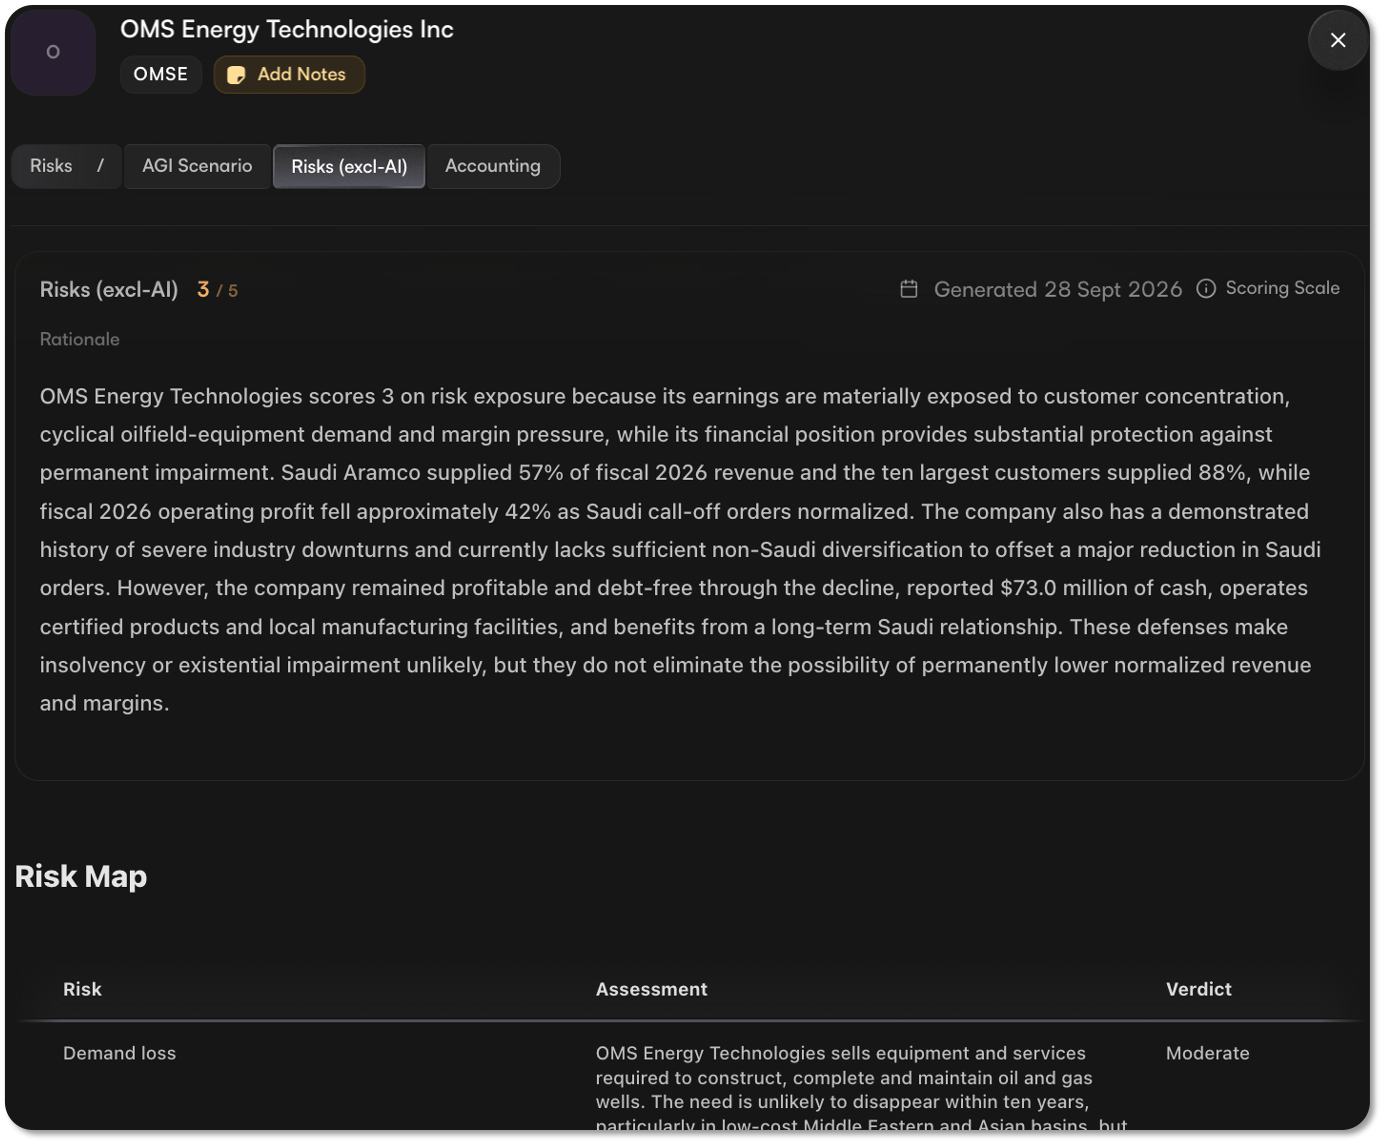
Saudi Aramco accounted for 57% of group sales in FY26 and 67% in FY25. The market demands a heavy small-cap discount because a single procurement pause in Saudi Arabia directly hits earnings. If the company accelerates conversion of non-Saudi contract pipelines, particularly for Surface Wellhead Systems (SWS) and proprietary packers, we should see an instant rerating (it’s only upside).
In FY26, non-Saudi specialty connector sales rose 130%. OMS secured its first 10,000-PSI surface wellhead contracts in Pakistan, landed initial customer orders in Angola and Oman, and earned the new API Spec 11D1 certification for downhole retrievable packers.
Proving that OMS can generate $40m–$50m+ in recurring high-margin billings outside of Saudi Arabia will show institutional investors that the company is a multi-regional platform rather than an Aramco captive shop.
Material Weakness in Internal Controls and Visibility
In its Form 20-F for FY26, management disclosed a continuing material weakness in internal control over financial reporting, citing a shortage of personnel experienced in IFRS and SEC accounting guidelines following its recent transition to public markets. Not sure how to fix this beyond a clean third-party audit, but addressing this should change perception and clarify what a red flag is for most institutional players.
This is a tiny company, but it’s one of those that, with a bit of coverage, would zoom as it checks most of the criteria that institutional holders look for.
💰 What’s It Worth?
We used a demanding 13% discount rate to account for its small-cap size and customer concentration with Saudi Aramco, along with a 2% perpetual growth rate.
Base Case [$4.30] (126% Upside)
On the operating side, we assumed revenue rebounds gradually from its FY26 post-order normalization ($155.9m) toward $200m, while maintaining operating margins that level out at 21.5%.
Setting aside cash to upgrade equipment across its plants and rebuild raw steel inventory, OMS projects to generate $27m to $33m in annual FCF, giving its underlying operations an enterprise value of $272.4m.
After adding back OMS’s $154.3m cash and subtracting minority partner interests and facility leases, the total net value to shareholders reaches $412.5m.
Divided across its 42.45m shares, that’s an intrinsic (fair) value of $9.72 per share.
Even under harsher stress tests with higher discount rates and slower growth, fair value remains comfortably in the $8.30 to $9.30 range.
Note that unrestricted cash alone accounts for $3.58 (~80% of the entire stock price), meaning you are effectively buying OMS’s manufacturing hubs, proprietary connection designs, and multi-year national oil company contracts for a stub enterprise value of just ~$40m.
We’ll leave you to do the super complex math on EV/FCF figures. 😉
Bear Case [$3.50]
We really don’t think a bear case is necessary here. Given the nature of their operations, it would be very surprising if the company lost money. At the end of the day, the stock has a natural floor value anchored by its net cash.
Don’t forget to check out Baseline. Take it for a spin using code HERMIT for that sweet 20% off.
What makes you think there is gonna be any capital return to shareholders ?
The call transcripts In June and last November indicate M&A to expand the size of the company nothing else.
H2: "Our cash reserves are contributing meaningful finance income and our overall financial strength positions us to invest in growth. Our priority is disciplined development that builds on what we already do well. To that end, we have initiated a review of potential opportunities to extend our portfolio, mapping them to our core strength by both fit and time horizon.
In the nearer term, this has pointed us to completion and production technologies adjacent to our existing portfolio, such as artificial lift and building on our recent certification package.
Over the longer term, we are exploring areas in the energy transition space where our subsurface and engineering expertise is relevant, such as geothermal and carbon capture and storage. This is a structured exploratory process, not a commitment to any given transaction or sector. We are confident in our ability to put this balance sheet to work on long-term, high-return opportunities without the need to raise additional equity."
H1: "With this period's strong cash generation, a healthy debt-free balance sheet, and a solid order pipeline in place, we are well positioned to start deploying capital to drive long-term growth. We are currently evaluating strategic opportunities that will expand our manufacturing capability and international footprint. We also continue to strengthen our engineering teams in Singapore and Indonesia, with plans to expand to other operating jurisdictions."
"We will remain focused on maintaining profitability, preserving balance sheet strength, and prudently deploying capital towards long-term, high-return opportunities that support sustainable growth and build value for our stakeholders."
I don't see this going anywhere with $100K nominal Volume, the geography, the segment, the customer concentration, the 62% CEO Ownership.
With Aramco's jackup suspensions the obvious risk, how much of OMSE's revenue depends on Saudi call-offs versus Southeast Asia? That split seems to decide whether the cigar-butt label holds.