

It’s only taken an entire quarter, but at last we have a candidate that checks every single box: circle of competence, geographic edge, and strict pricing hurdles.
There’s really no point in introducing these guys...
⭐ Overall Grade: 9.5 / 10
It’s just a freaking great business.
Let’s break it down.
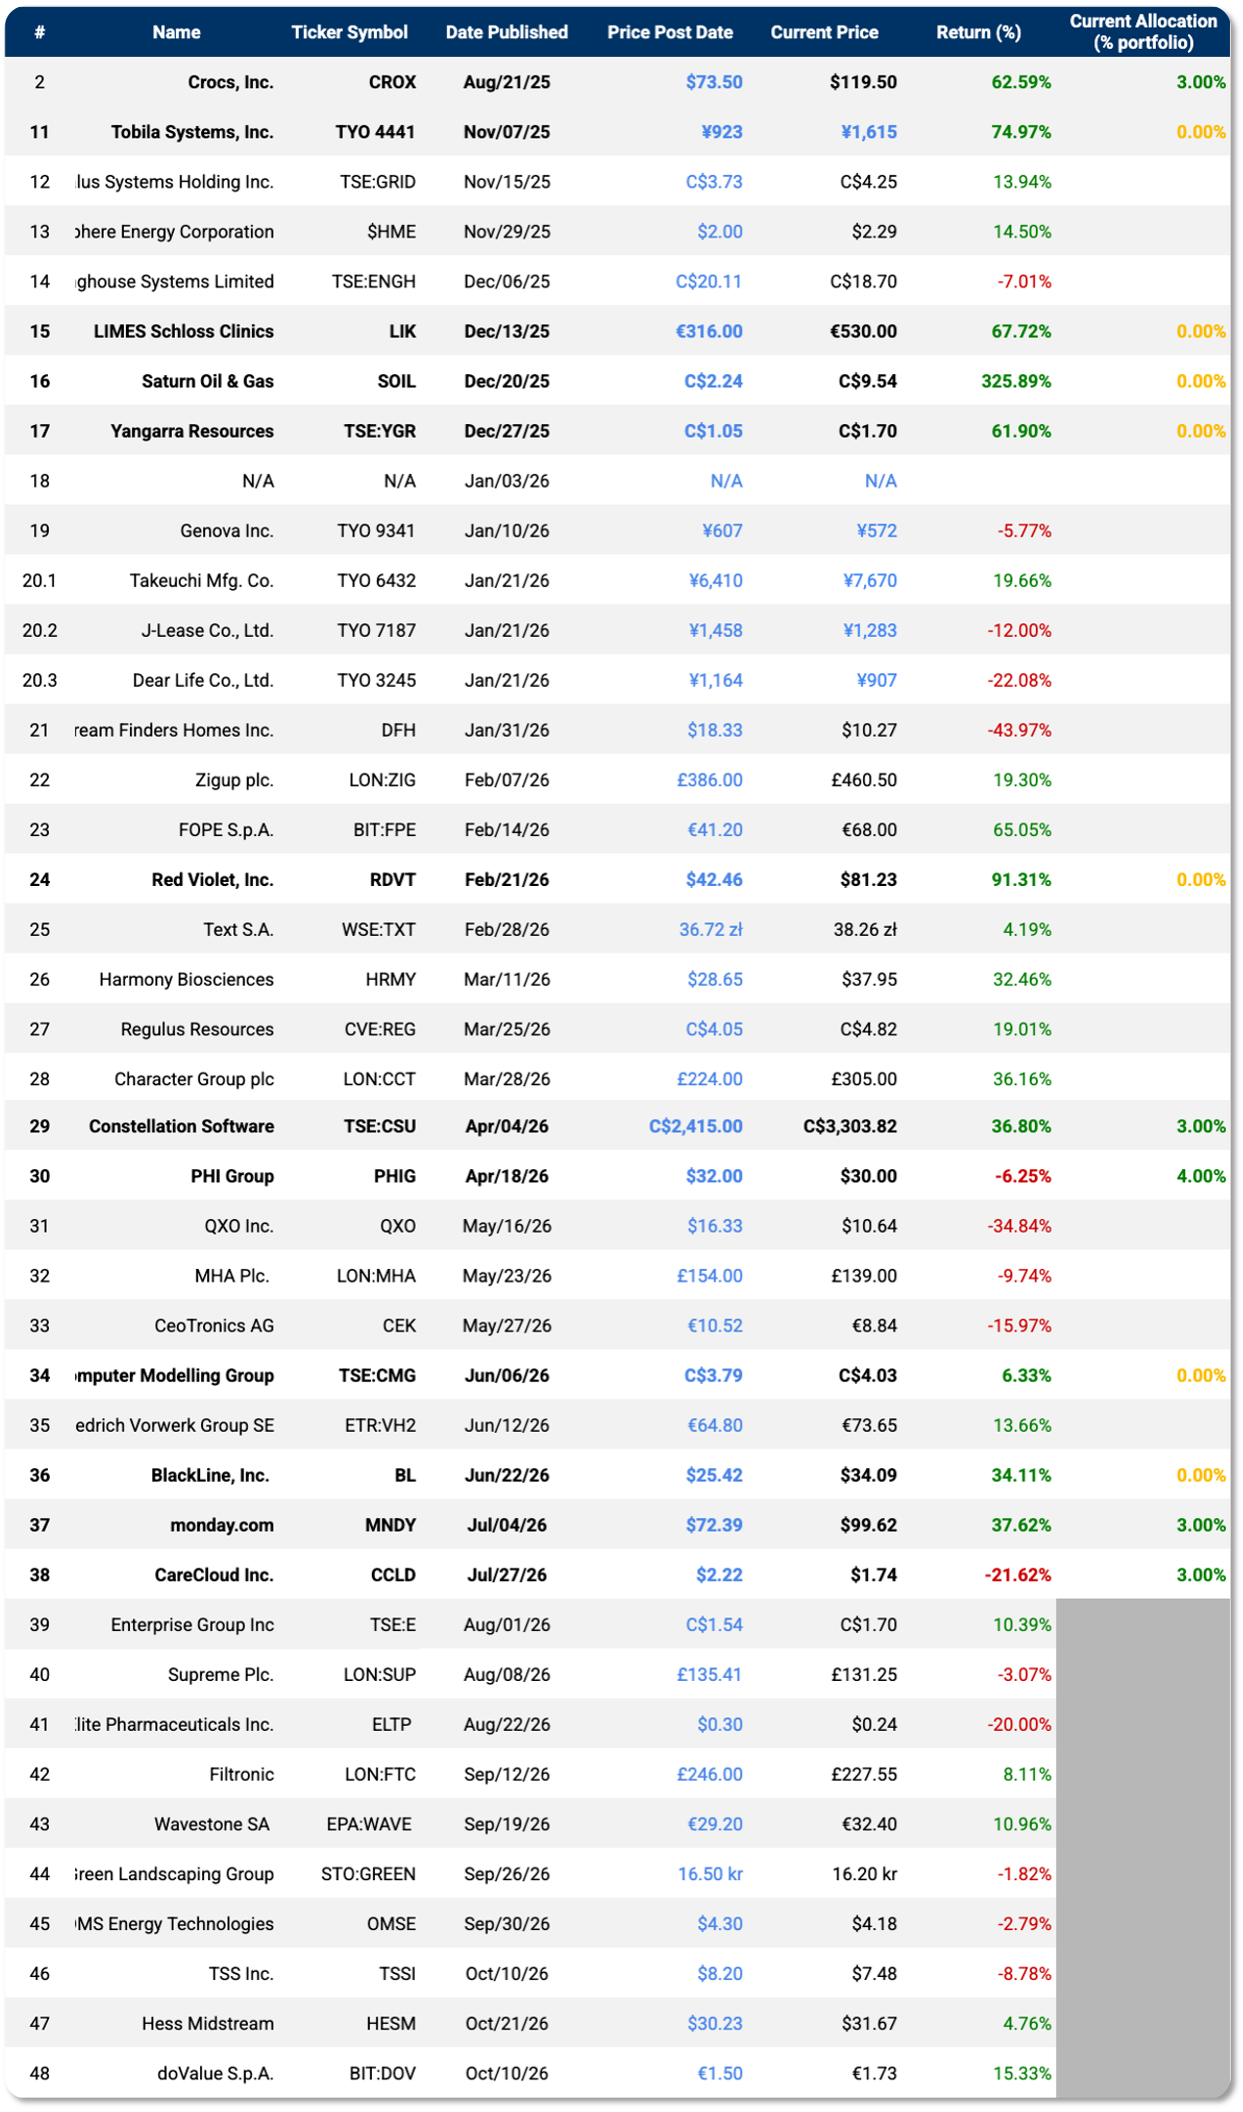
As we now do every week for transparency, here is our list of past Pick of the Week posts and their returns since publishing:
All picks (equally weighted): +21.78%

Pick of the Week. A curated series of high-conviction research on companies currently under our microscope. We screen for specific dislocations where the market has mispriced the balance sheet or earnings power (or both).
None of the following should be construed as investment advice. Please consult a financial advisor before making any investment decision. You will find a full disclaimer at the end of this post.


🏦 doValue S.p.A. ($DOV)
⭐ Overall Grade: 9.5 / 10
doValue is the leading independent credit and loan servicer in Southern Europe (ranking #1 in Italy, Greece, and Cyprus) and, following the transformational acquisition of coeo Group (closed April 2026), #2 in digital receivables in the DACH region.
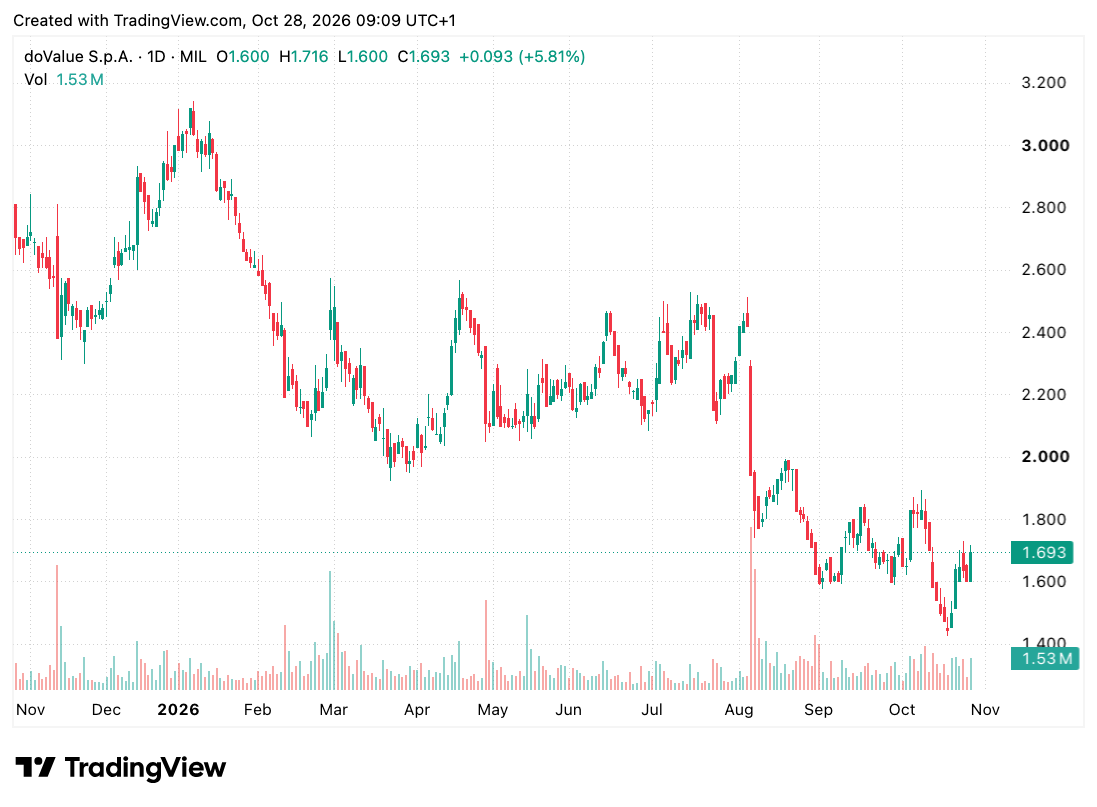
Despite operating with an asset-light, pure-fee servicing model (bearing essentially zero balance-sheet credit risk on its core NPE books), the stock has suffered a ~90% drawdown since its IPO peak.
The market views doValue as a ‘melting ice cube’, pricing in an endless terminal run-off of legacy non-performing loan (NPL) books caused by European banking cleanup and record-low default rates.
At ~€1.60–€1.80 per share (~€305m–€345m market cap), the stock trades at ~3.5x to 5.0x normalized FCF.

The consensus (price) treats the business as a balance-sheet-heavy debt buyer (analogous to distressed peers like Intrum or its Norwegian acquisition Lindorff) rather than a pure-fee asset manager.
Sell-side models extrapolate the cyclical trough of Southern European NPL volumes into perpetuity.
Both of these assumptions are clearly wrong, but more importantly, the market attaches essentially zero option value to: