

We just moved to a new domain, and algorithms hate sudden changes. If you leave this in the Promotions tab, the odds are high that our upcoming analyses will quietly slip past you without you ever knowing.
How would you feel about dragging this over to your Primary inbox right now?
And while you’re there… hit Reply with the one ticker keeping you up at night and what makes it worth a teardown. What’s the biggest reason we shouldn’t cover it?
We are releasing a comprehensive update on the Car Distribution and Logistics segment (with a North American focus) centered around Carvana ($CVNA), Copart ($CPRT), and Credit Acceptance ($CACC), while incorporating insider perspectives on roughly a dozen other listed companies referenced throughout the piece.
This write-up includes key takeaways and contextualized transcripts from four interviews conducted a few weeks ago.
Take your time with these, as the reading time of this article exceeds 2 hours. We recommend going over the takeaways and then dissecting each interview slowly, one by one.
Because these businesses are already well covered, we are skipping the standard overview and jumping straight into the insights from our three direct 1-on-1 conversations and one third-party interview.

Priority Briefings. Investing is dynamic, so our research never sits still. We don’t file a report and walk away; we maintain an active, ongoing dialogue with the key stakeholders and management teams of our past, present, and future holdings.
Think of these briefs as your “insider access” to those calls. We bring you direct contextualized highlights and actionable updates. You’ll see exactly how the business is evolving in real-time, long before it hits the quarterly report.
This series is exclusively for 🧙♂️ Inner Circle members
None of the following should be construed as investment advice. Please consult a financial advisor before making any investment decision. You will find a full disclaimer at the end of this post.

In Conversation with Insiders
Key Takeaways and Insights
We provide context on who these experts are at the top of each interview in the full transcript section.
This is a clear example of combining warm introductions with expert networks, but more importantly, it illustrates the sheer amount of work that goes into every single write-up.
Most of these primary checks never see the light of day, yet they remain essential to the process. Sometimes they lead nowhere; other times they completely rewarp our perspective.
The following conversations fall squarely into the second camp.
Copart ($CPRT)
Brad Stewart’s account confirms why Copart behaves more like an entrenched liquidity monopoly than a standard auctioneer.
Takeaway #1. A shadow dealer in the making
Your typical person views Copart as a junkyard for wrecked cars, but its fastest-growing profit engine is selling clean, drivable vehicles that command double the sale price of a total-loss clunker.
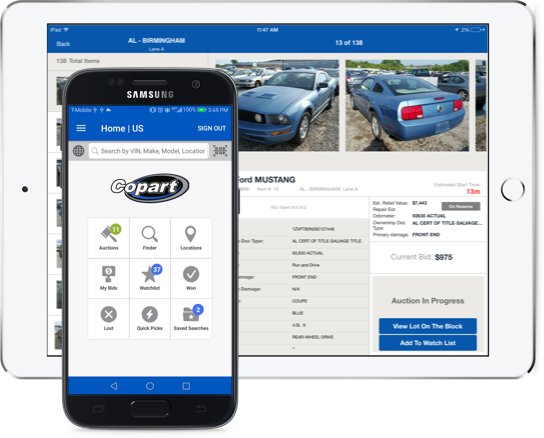
Copart Dealer Services (CDS) processes roughly 300,000 units annually, while its higher-spec whole-car channel, Blue Car, runs around 8,000 units. While this is a small fraction of the ~12m commercial wholesale cars remarketed annually in the US, it represents a massive TAM expansion beyond the saturated insurance salvage pool.
The unit economics are driven by Copart’s tiered member fee schedule, where fees scale with the Average Selling Price (ASP).
While a standard insurance total-loss vehicle generates an ASP of ~$2,900, a CDS dealer car averages ~$5,300, and a Blue Car unit reaches ~$6,800.
Because member transaction fees are back-end loaded and scale with ASP, capturing whole-car inventory compounds incremental EBIT margins with negligible added variable cost.
To unlock dealer trust on drivable cars, Blue Car instituted 45-point condition inspections and a 45-day arbitration policy. Similar to Carvana, this systematically neutralizes the historic “as-is, buyer-beware” penalty that depressed whole-car bids. In the end, it’s all a trust-building exercise.
Takeaway #2. There’s a lot to say about offshore cost arbitraging
Copart is an active global brokering desk where 90% of dealer car deals are negotiated after the virtual auction ends.
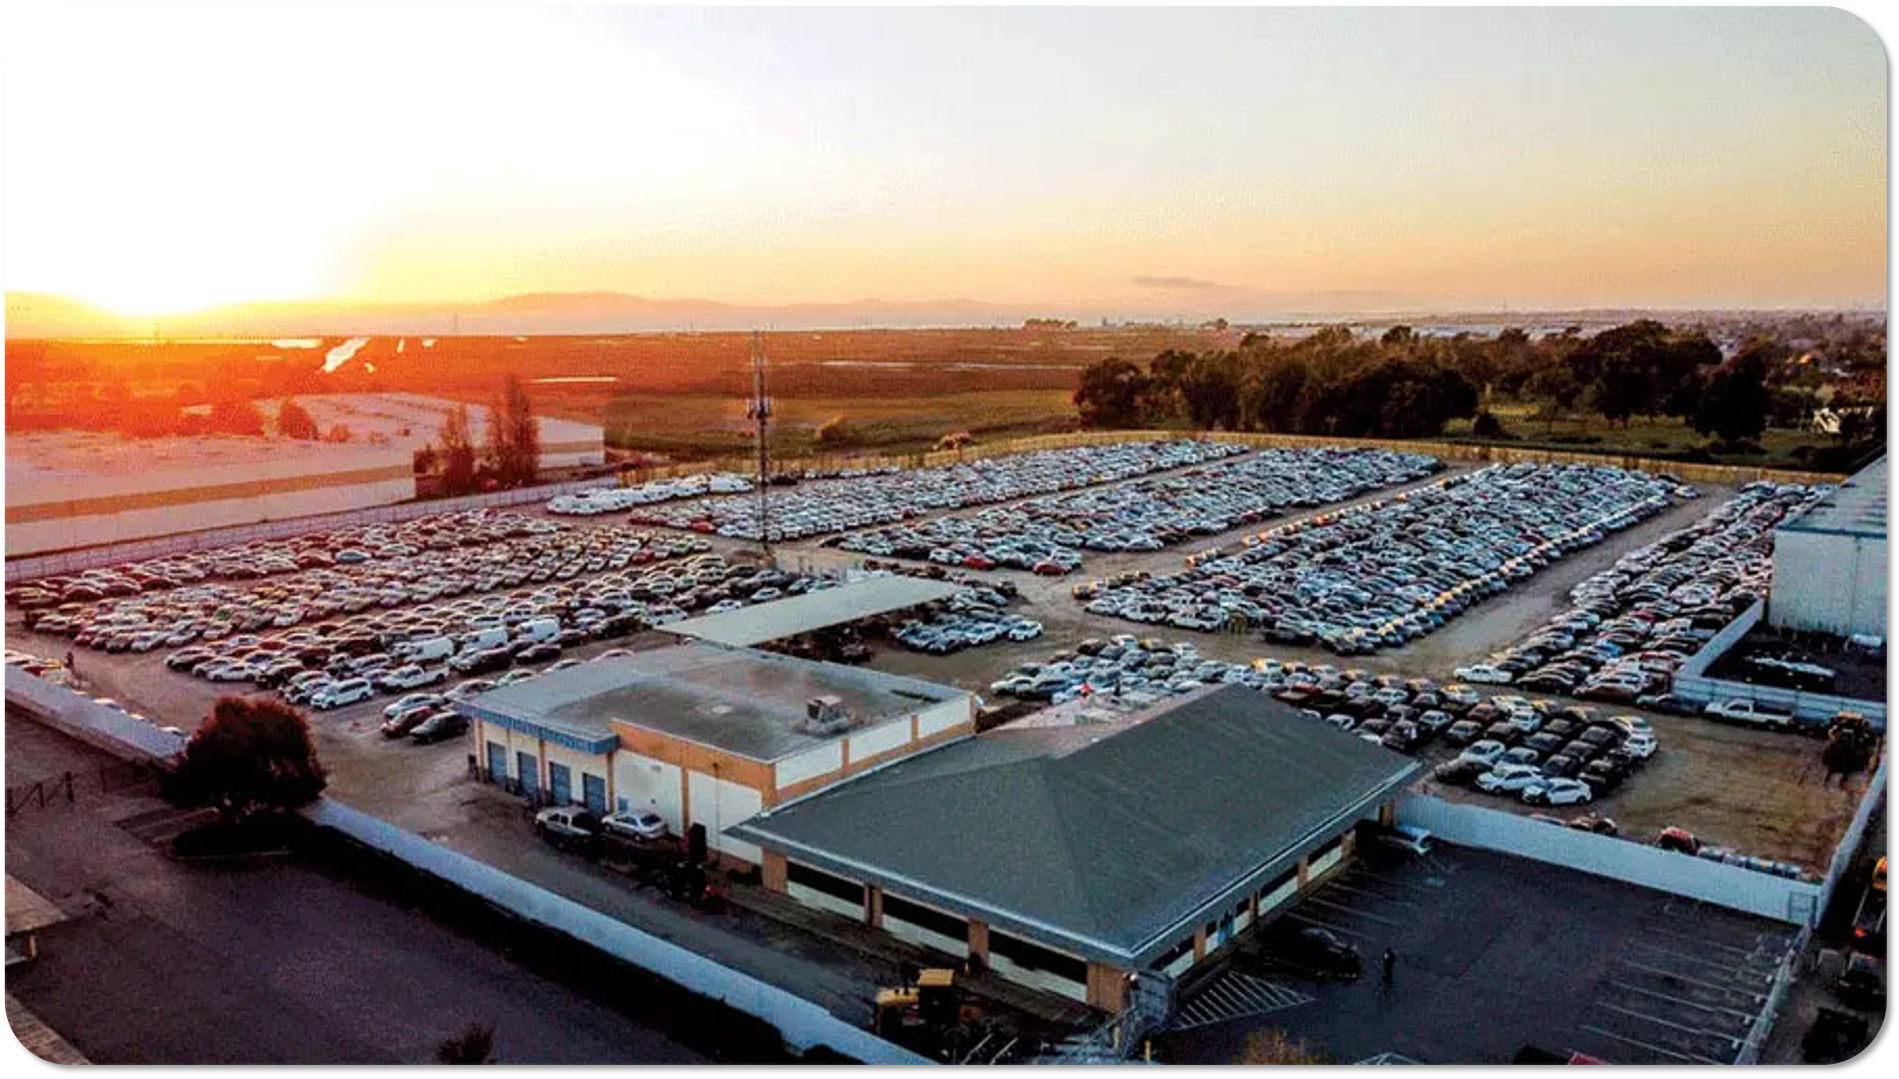
39% of all vehicles sold across Copart’s 200+ yards are exported to international buyers spanning 190 countries. These global buyers possess fundamentally different salvage economics, lower offshore repair labor costs, and resourceful workarounds (such as cutting unibodies into sections to clear customs as low-tariff “parts” before re-welding them abroad).
Crucially, roughly 90% of CDS inventory does not clear at the reserve during the live auction; it is completed through post-sale intermediation.
Copart’s internal platform captures all bidder identities and pricing thresholds down the line. Dedicated sales reps call the second- and third-highest bidders overseas (e.g., in Dubai or Eastern Europe) to negotiate directly between the seller’s reserve and the runner-up bids.